Selling a winning investment inside your IRA generally does not trigger an immediate tax bill. Taking that money out of the account can.
That distinction matters whether you made $5,000 or $500,000. A successful investment can strengthen your retirement plans, but turning the proceeds into spending money without checking the rules could leave you with taxes, an early-withdrawal penalty or even higher Medicare premiums.
Before deciding what to buy next, separate three decisions: selling the investment, reinvesting the proceeds and withdrawing money. Each serves a different purpose, and the tax consequences can be very different.
You Can Sell Without Taking the Money Out
When you sell an ordinary stock inside a traditional IRA, the proceeds generally stay within the account. You can hold that money in cash or reinvest it without creating an immediate taxable withdrawal.
That gives you room to change investments, reduce your exposure to one company or set aside money for future retirement spending. You do not have to withdraw the proceeds just because you sold the stock.
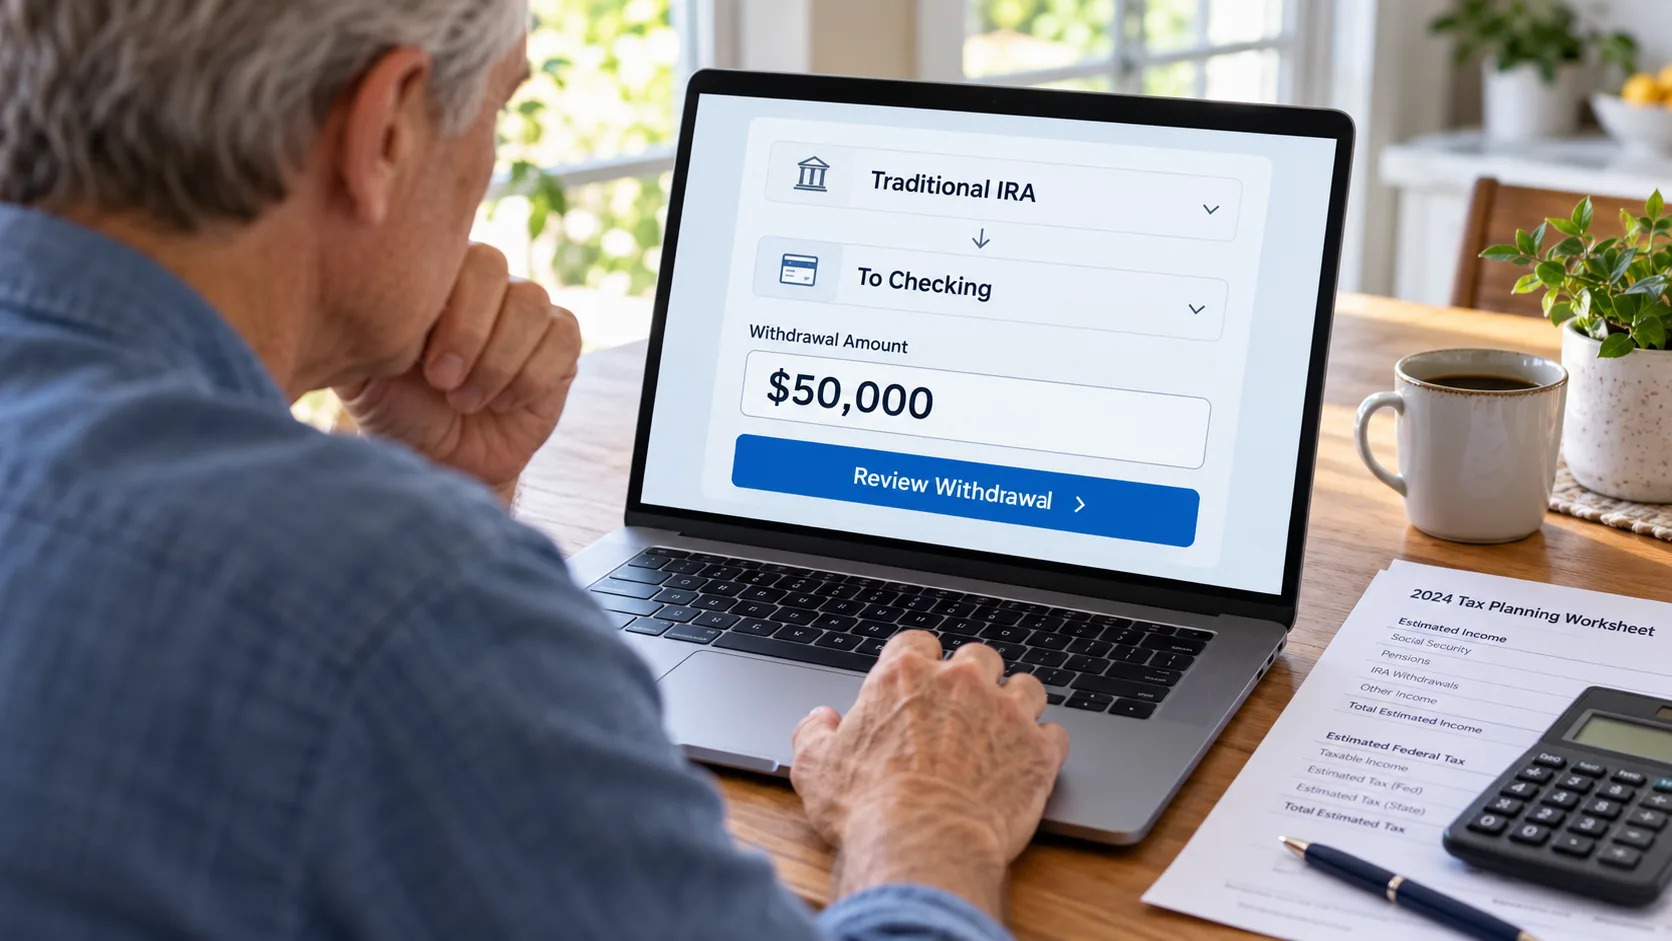
Moving that money from your traditional IRA into your checking account for spending is a separate transaction. That withdrawal is generally taxable, except for any portion attributable to properly documented after-tax contributions.
The distinction is especially important after a big gain. Money available to trade inside your IRA is not necessarily money you can spend without tax consequences.
The Tax Bill Can Apply to More Than the Profit
Suppose you bought a stock for $25,000 inside your traditional IRA and later sold it for $75,000. You made a $50,000 investment gain, and keeping the proceeds inside the IRA generally avoids an immediate tax bill.
Now suppose you withdraw the entire $75,000 to spend. If your traditional IRAs contain only pretax money and earnings, the full $75,000 generally counts as taxable income.
The original $25,000 stock purchase does not become a tax-free portion of the withdrawal. After-tax IRA contributions can make part of a distribution tax-free, but that calculation follows IRA rules rather than the purchase price of the stock you sold.
There is another difference from investing in a regular brokerage account: Taxable traditional IRA withdrawals are treated as ordinary income. Holding the stock for several years does not make the withdrawal eligible for favorable long-term capital-gains rates.
The Penalty Is Only One Part of the Risk
Before age 59½, the taxable portion of a traditional IRA withdrawal generally faces an additional 10% tax unless an exception applies. A fully taxable $50,000 early withdrawal could therefore generate a $5,000 additional tax, on top of regular income taxes.
Reaching age 59½ generally removes that age-based penalty. The ordinary-income tax treatment remains, and a large withdrawal can push some of your income into a higher tax bracket.
For people on Medicare, the consequences can extend beyond the tax return. Higher income can trigger income-related surcharges on Part B and prescription drug coverage. Those calculations generally use tax-return information from two years earlier, so the higher premiums can arrive well after the money was spent.
Roth IRAs follow different rules. Qualified withdrawals are tax-free, generally after meeting the five-year requirement and reaching age 59½, although other qualifying circumstances exist. Early withdrawals involving earnings or converted amounts require closer attention.
Check which kind of IRA you own before assuming that a withdrawal will be taxable or tax-free.
What a $500,000 Stock Sale Really Changes
Consider someone who sells a stock and now has $500,000 in IRA cash. That is a meaningful amount of money, but the sale itself did not suddenly add $500,000 to the retirement account.
The shares already had that value immediately before the sale. Selling exchanged the stock for cash, so any retirement projection that already included the shares should not add the proceeds again.
What changed is the opportunity to use that value differently. The money could support a more diversified portfolio, reduce dependence on one company or help prepare for upcoming withdrawals.
To put the balance in spending terms, 3% of $500,000 is $15,000. Four percent is $20,000, or about $1,667 a month, before applicable taxes.
These are first-year withdrawal illustrations, not guaranteed income or recommended withdrawal rates. Withdrawals can include principal, and sustainability depends on investment results, inflation, retirement length, fees and spending flexibility.
Compare those amounts with the gap between your expected expenses and income from Social Security, pensions or other sources. That calculation tells you more about your retirement options than the stock’s gain alone.
Give the Money a Job Before Reinvesting
Protect Money You Will Need Soon
Money intended for upcoming retirement withdrawals deserves a different approach from money you can leave invested for another decade. Cash and high-quality, short-term holdings can help reduce the chance that you will need to sell stocks during a downturn.
Keeping everything in cash indefinitely brings its own risk. If returns fail to keep pace with inflation, the money gradually buys less.
Start with your spending needs and timeline. Then decide how much should remain readily available and how much can stay invested for longer-term growth.
Look Across the Household’s Accounts
Your IRA should fit alongside your workplace retirement plan, taxable investments and, where relevant, your spouse’s savings. Each account does not need to hold an identical mix of investments.
For example, a household that already owns substantial stock investments elsewhere may use some IRA proceeds to strengthen its bond or cash allocation. Another household with a longer timeline may still need significant growth exposure.
Diversification can reduce dependence on a single investment, although it cannot eliminate losses. The useful question is how the entire portfolio supports the household’s goals.
A winning investment may also create an opportunity to take less risk. When your plan is better funded, chasing another big winner deserves scrutiny rather than becoming the automatic next step.
Check the Costs and the Calendar
Three details deserve attention before the proceeds settle into a new strategy.
What is the cash earning? Brokerage cash options can have very different yields. Compare the default arrangement with alternatives available inside the IRA, paying attention to fees, access and protections. A money market mutual fund, for example, does not have FDIC deposit insurance.
What are you paying? A 1% annual advisory fee on $500,000 equals $5,000 at that balance, potentially before underlying investment expenses. Ask what services are included and whether the same fee applies to uninvested cash.
What withdrawals are coming? Once required minimum distribution rules apply, the calculation generally uses the account’s balance from the previous December 31. Investment growth can increase future required withdrawals, making tax planning more important as the account grows.
Before a large discretionary withdrawal, have a tax professional compare the proposed amount with your other income and upcoming needs. Depending on your circumstances, spreading withdrawals across tax years may produce a different result from taking everything at once.
Keep More of What You Made
A successful investment should give you more choices about your future. Protect those choices by checking the taxes before moving money out and checking the retirement plan before putting it back to work.
There is no need to avoid every taxable withdrawal. The account exists to help fund your life, and paying some tax may be part of using it as intended.
The expensive mistake is making the withdrawal first and discovering the consequences later. Know what you need, what you will owe and what the remaining money must do for you.
This article is for general educational purposes. Investment and tax decisions should reflect your circumstances.
About Author