Medical technology giant Stryker (NYSE: SYK) has fallen more than 20% from its 52-week high, raising an interesting question for investors: Is the selloff an opportunity to buy a leading healthcare company at a discount?
Stryker, which generates more than $25 billion in annual revenue, manufactures orthopedic implants, surgical equipment and robotic systems. Despite a strong history of growth, its shares have come under pressure from operational setbacks and concerns about healthcare spending.
Why Stryker Stock Has Fallen
Several challenges have weighed on the stock, including a March cyberattack that disrupted operations and supply problems affecting its Inari Medical business. Investors have also expressed concerns about government healthcare funding and the potential impact on medical procedure volumes.
Shares recently traded around $307, approximately 22% below their 52-week high of $392.55.
However, the company’s underlying business remains strong. Stryker has delivered approximately 10% annual organic revenue growth over the past five years, outperforming the broader medical technology industry by roughly four percentage points annually.
Three Reasons Investors Are Taking Another Look
1. A Dominant Position in Medical Technology
Stryker holds leading positions across numerous medical equipment markets. Its extensive hospital relationships, broad product portfolio and roughly 60 acquisitions over the past decade create competitive advantages that are difficult for smaller rivals to match.
2. Robotic Surgery Offers Long-Term Growth
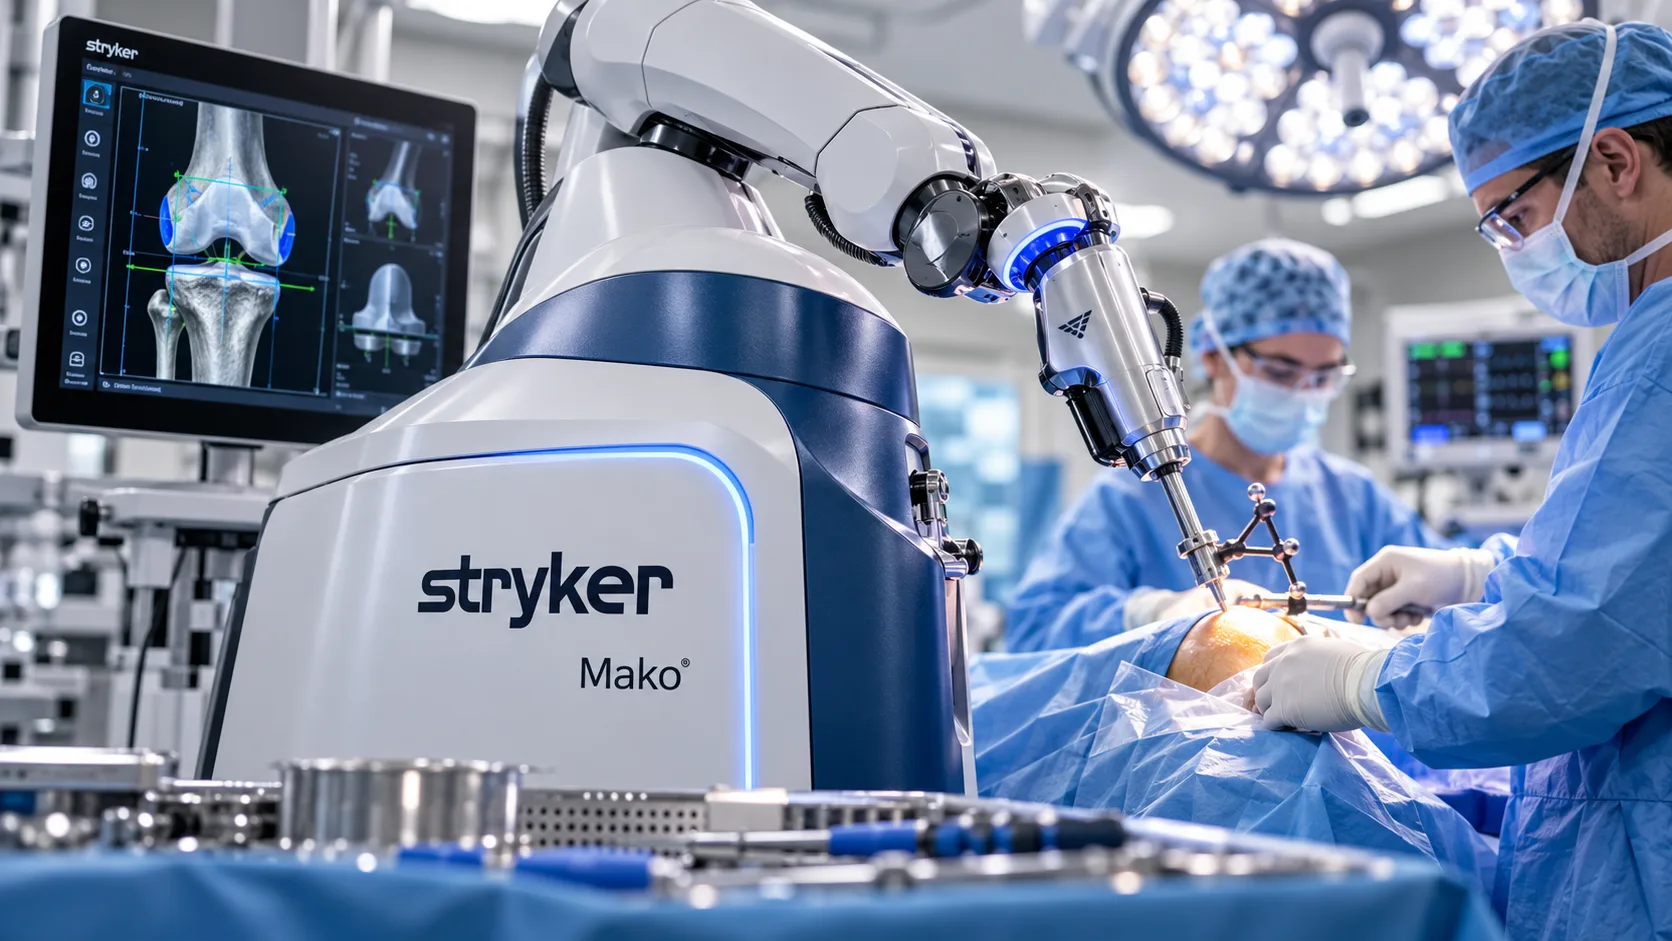
Stryker’s Mako robotic-assisted surgery system helps surgeons perform joint replacements with greater precision. An aging population and growing adoption of robotic procedures could drive demand for years.
The shift toward outpatient surgical centers also creates opportunities for the company’s equipment and technology.
3. A Potential Valuation Opportunity
Stryker has historically commanded a premium valuation of approximately 24 to 25 times forward earnings, reflecting its consistent growth and market leadership.
The recent selloff has brought shares below that historical valuation range. If operational problems ease and earnings growth accelerates, investors could benefit from both stronger profits and a recovery in the stock’s valuation.
What Could Drive the Stock Higher?
Investors will be watching for improved manufacturing operations, resolution of supply disruptions and continued growth in robotic surgery.
A leadership transition is also approaching. Spencer Stiles, a 27-year company veteran, will replace Kevin Lobo as CEO on January 1, 2027, while Lobo becomes executive chairman. The planned succession provides continuity as Stryker works through its challenges.
The risks remain meaningful. Further operational disruptions, slower hospital spending or reductions in government healthcare funding could pressure earnings and delay a recovery.
The Investor Takeaway
Stryker’s stock has suffered a substantial decline, but its competitive position and long-term growth opportunities remain attractive.
For investors seeking healthcare exposure, the combination of an aging population, expanding robotic surgery and a discounted valuation makes Stryker worth a closer look. The key question is whether management can restore normal operations and maintain its historical growth rate.
About Author