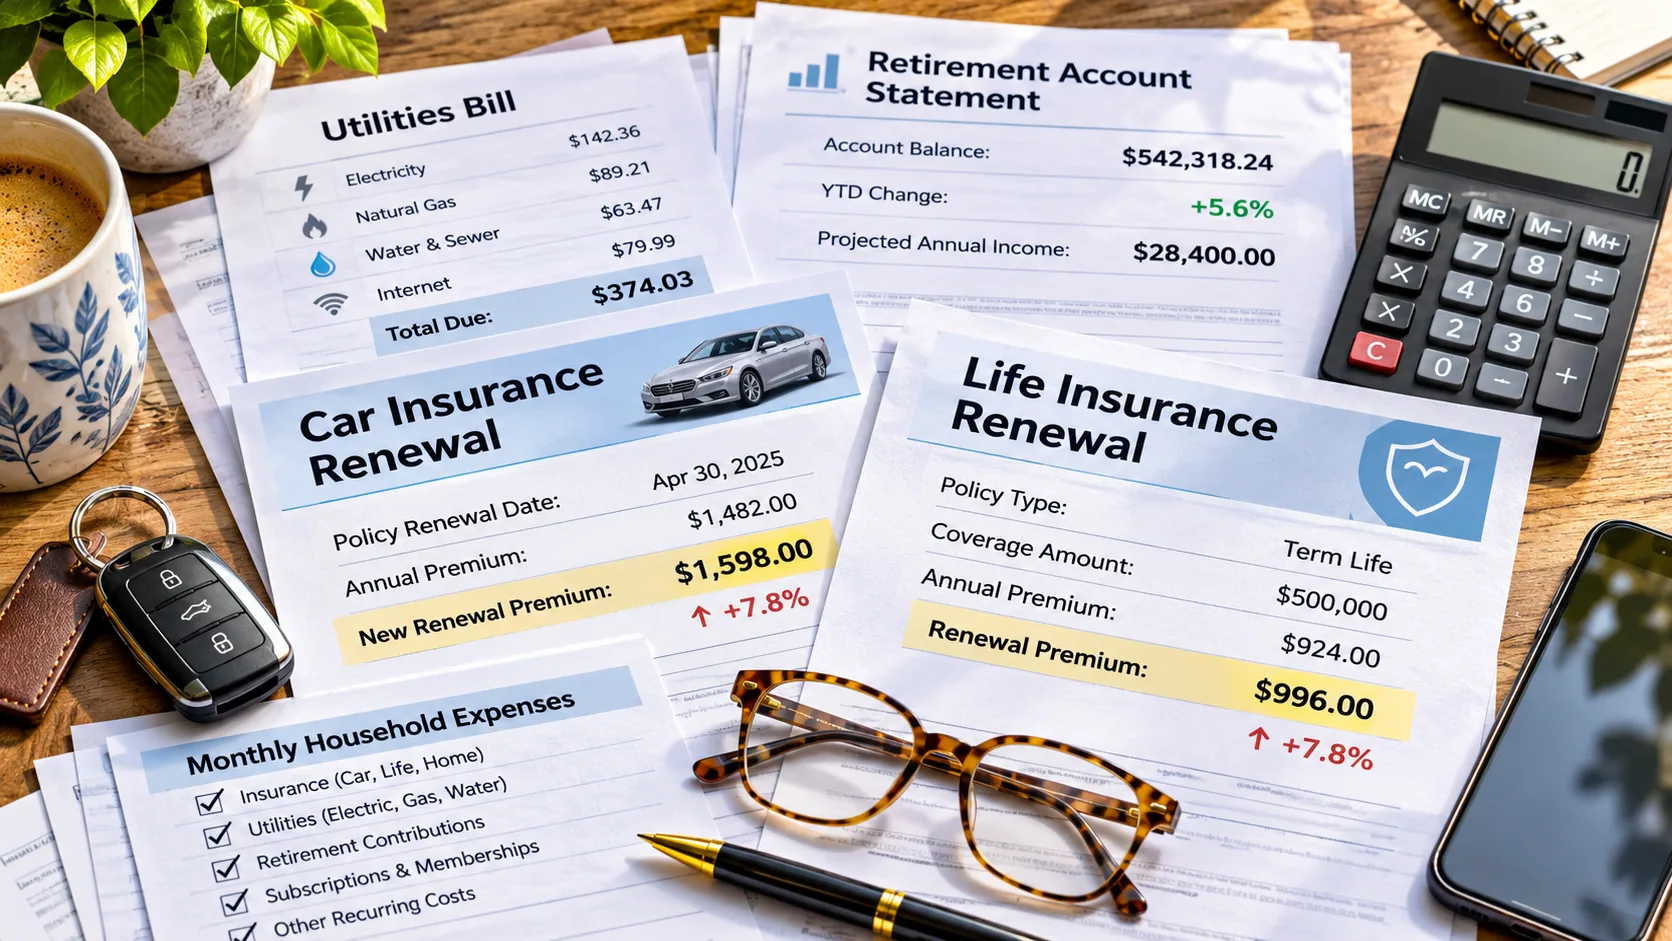
You could be losing hundreds or even thousands of dollars a year without realizing it. From overpriced insurance to overlooked retirement expenses, these seven common financial mistakes are worth checking before they take another dollar from your savings.
Most Americans spend years building their retirement savings. They watch the stock market, contribute to retirement accounts, and carefully consider major purchases. Yet some of the easiest opportunities to improve their finances may be hiding in bills they already pay.
The problem is that once a financial decision has been made, people often stop thinking about it. An insurance policy renews automatically. Money sits in the same bank account. Investment fees quietly reduce returns.
These expenses may seem insignificant individually. Over five, ten, or twenty years, however, they can add up to a substantial amount of money.
Here are seven financial mistakes worth reviewing, particularly if you’re over 50.
1. Staying With the Same Car Insurance Company Without Comparing Rates
When was the last time you checked whether you’re paying too much for car insurance?
If you can’t remember, this could be one of the easiest financial mistakes to investigate.
Many drivers stay with the same insurance company for years. Their coverage renews automatically, the payment comes out of their bank account, and they rarely question whether they’re still getting a competitive rate.
Insurance companies don’t all calculate premiums the same way. Your driving record, location, vehicle, annual mileage, and other factors can affect what each company charges.
That means two insurers may offer substantially different prices for similar coverage.
And here’s something many drivers overlook: You could be paying more than necessary even if you’ve never had an accident or received a speeding ticket.
As your circumstances change, so can your insurance needs. You may be driving fewer miles, working from home, or qualifying for discounts you haven’t investigated.
Consider how even a relatively modest reduction could affect your finances:
- Save $30 a month: That’s $360 annually.
- Save $50 a month: That’s $600 annually.
- Save $75 a month: That’s $900 annually.
Those are hypothetical examples, but they illustrate why comparing rates can be worthwhile.
The National Association of Insurance Commissioners recommends shopping around because companies can charge different premiums for comparable coverage.
Fortunately, comparing options no longer requires calling insurance agencies one at a time.
Compare.com works with more than 100 insurance partners and allows drivers to review personalized quotes from multiple companies. Comparing quotes is free, and there’s no obligation to purchase a policy.
Before paying another car insurance bill, find out whether another company could offer a better rate.
Are You Paying Too Much for Car Insurance?
Your current insurer may not offer your best available rate. Compare quotes and see whether you could save.
COMPARE CAR INSURANCE RATES → Free to compare • No obligation to purchase2. Assuming You No Longer Need Life Insurance After 50
Life insurance is often something people purchase when they’re younger, raising children, or buying their first home.
Your children may be grown, but your spouse could still depend on your income. You might have a mortgage, outstanding debts, or other financial obligations. And your family could face significant expenses after your death.
For some households, existing savings may be sufficient to handle these responsibilities. For others, life insurance can provide important financial protection.
The mistake is assuming that a policy purchased twenty years ago still meets your needs, or that obtaining coverage later in life is no longer worth exploring.
Three questions can help you determine whether it’s time for a review:
- Would your spouse or another family member face financial difficulty without your income?
- Are there remaining debts or expenses you’d want covered?
- Would your existing savings be enough to handle immediate expenses and support your family’s financial needs?
If you answered yes to the first two questions or aren’t sure about the third, reviewing your life insurance options may be worthwhile.
There are different types of coverage available, including term life insurance and permanent policies. The right choice depends on your age, health, financial obligations, budget, and how long you need protection.
You may also discover that the amount of coverage you need today is different from what you needed twenty years ago.
Fidelity Life offers life insurance options and an opportunity to explore coverage based on your circumstances.
You don’t need to commit to a new policy just to investigate your options. Understanding what’s available is a useful first step.
Over 50? Is Your Family Protected?
Life changes. Your insurance needs may have changed too. Explore coverage options and find out what’s available to you.
EXPLORE LIFE INSURANCE OPTIONS → Explore coverage and request a quote. Eligibility varies.3. Leaving Too Much Money in a Savings Account That Pays Almost Nothing
Having cash available for emergencies and unexpected expenses is essential, especially as retirement approaches.
But where you keep that money matters.
Some traditional savings accounts pay very little interest, while other savings accounts and money market deposit accounts may offer substantially higher yields.
Consider a simple example.
If you have $40,000 in savings earning 0.10% annually, you would earn approximately $40 in interest over one year.
If that same balance earned 4%, it would generate approximately $1,600 over a year, assuming the rate remained unchanged.
That’s a difference of $1,560 before taxes.
These are illustrative rates, and actual yields change over time. Still, the example demonstrates how leaving money in an uncompetitive account can create a considerable opportunity cost.
Review the annual percentage yield on your savings account, any account fees, and the requirements for earning the advertised rate.
It’s also important to understand deposit protection. The FDIC generally insures eligible deposits up to $250,000 per depositor, per insured bank, for each ownership category.
For retirees, the goal should be to keep emergency savings accessible while earning a competitive return without taking unnecessary risk.
4. Paying for Subscriptions and Services You Barely Use
A few dollars here and there might not seem like much, especially when payments are automatically deducted from a checking account or credit card.
But those small charges can become surprisingly expensive.
Streaming services, premium memberships, software subscriptions, mobile apps, and other recurring expenses can continue for months or years after you’ve stopped using them regularly.
For example, consider someone paying for:
- Two unused subscriptions at $15 each per month.
- A premium membership costing $20 per month.
- An unnecessary service costing $25 per month.
That’s $75 monthly, or $900 a year.
And over five years, those expenses would total $4,500 if the prices remained unchanged.
Reviewing your credit card and bank statements for recurring transactions can uncover expenses you’ve simply forgotten about.
Canceling unused services is one of the few ways to improve your monthly cash flow without changing your investments, taking additional risk, or reducing your quality of life.
5. Overlooking Fees That Quietly Reduce Your Retirement Savings
Investment fees are among the most easily overlooked expenses in retirement planning.
Mutual funds, exchange-traded funds, retirement plans, and financial advisory services can all involve ongoing charges.
Those fees may appear small when expressed as a percentage. Over time, however, they can have a meaningful impact on your portfolio.
The Securities and Exchange Commission illustrates the difference using a hypothetical $100,000 portfolio growing at 4% annually before fees.
After twenty years, the estimated account values would be approximately:
| Annual Fee | Portfolio Value |
|---|---|
| 0.25% | $208,000 |
| 0.50% | $198,000 |
| 1.00% | $179,000 |
That’s a difference of approximately $29,000 between the lowest-fee and highest-fee scenarios.
The reason is straightforward. Money paid in fees leaves your account and can no longer compound.
This doesn’t mean the cheapest investment is automatically the best. Investment strategy, risk, performance, and professional advice also matter.
But understanding how much you’re paying is essential.
Check your retirement statements for expense ratios, advisory fees, administrative costs, and other ongoing charges. Ask whether less expensive options could accomplish your investment objectives.
6. Automatically Renewing Medicare Coverage Without Reviewing Your Options
For Americans approaching or already in retirement, healthcare expenses can have a major influence on their financial security.
Yet Medicare coverage is something many people review only when they first enroll.
That can be costly.
Medicare Advantage and Part D prescription drug plans can change their premiums, deductibles, formularies, provider networks, and other features from year to year.
A plan that worked well previously may no longer provide the most suitable combination of benefits and costs.
For example, a change in prescription drug coverage could increase annual expenses, even if the plan’s monthly premium looks attractive.
Medicare’s annual open enrollment period generally runs from October 15 through December 7, allowing eligible beneficiaries to review and change certain coverage options for the following year.
Before renewing, compare your estimated total annual costs, including premiums, deductibles, copayments, and prescription expenses.
Also confirm that your preferred doctors, pharmacies, and medications are covered under any plan you’re considering.
The cheapest monthly premium doesn’t necessarily mean the lowest overall healthcare cost.
7. Failing to Update Beneficiaries and Estate Planning Documents
One of the most important financial mistakes can have consequences that aren’t discovered until after someone dies.
People change jobs, open retirement accounts, get married, divorce, have children, and experience major changes in family circumstances.
But beneficiary designations and estate planning documents don’t always get updated along the way.
A retirement account might still name a former spouse. An old life insurance policy could list a beneficiary who is no longer appropriate. A will might fail to reflect changes in assets or family relationships.
These oversights can create delays, disputes, or unintended financial consequences for surviving family members.
A basic review should include beneficiary designations on retirement accounts, life insurance policies, and other accounts that allow beneficiaries.
Also consider whether your will, powers of attorney, and other estate documents still reflect your wishes.
Beneficiary rules and estate laws can be complicated, particularly when spouses, trusts, or blended families are involved. An estate planning professional can help identify potential problems before they become expensive.
The Two Financial Checks Worth Making First
Every mistake on this list deserves attention, but some are easier to investigate immediately than others.
Comparing insurance options is a practical place to begin because you can review what you’re currently paying, evaluate alternatives, and decide whether a change would benefit you.
Start with these two questions:
Are You Paying More Than Necessary for Car Insurance?
If you haven’t compared rates recently, you could be missing an opportunity to reduce a recurring expense. Even a $40 monthly reduction would put $480 back into your budget annually.
👉 COMPARE CAR INSURANCE RATES AND SEE IF YOU COULD SAVE
Would Your Family Be Financially Protected Without You?
If your life insurance coverage hasn’t been reviewed in years, now may be a good time to understand your options. Your family circumstances and financial obligations may have changed significantly.
👉 EXPLORE LIFE INSURANCE COVERAGE AND REQUEST A QUOTE
Small Financial Decisions Can Have a Big Impact on Retirement
Protecting your retirement savings involves more than choosing the right investments.
It also means making sure everyday expenses aren’t quietly consuming money that could be saved, invested, or used to enjoy retirement.
Consider the impact of finding $50 a month in car insurance savings and eliminating $50 in unnecessary recurring expenses.
That’s $1,200 annually, or $6,000 over five years, before considering any potential investment returns.
Those savings aren’t guaranteed, and every household’s situation is different. But the underlying lesson is valuable.
The money you stop wasting is money you can keep working for your future.
Before Your Next Car Insurance Bill Arrives…
Take a moment to compare insurance rates. You may find a better deal for the coverage you need.
SEE IF YOU COULD SAVE → Compare quotes for free • No obligationDisclosure: Global Market News may receive compensation when readers click certain links or purchase products or services through this article. Insurance quotes, rates, savings, and availability vary by individual circumstances. This article is for general informational purposes and does not constitute personalized financial or insurance advice.
About Author