New 401(k) contribution limits could allow some older workers to put away more than $37,000 next year, while high earners face an important tax rule.
Americans saving for retirement will be able to put more money into their 401(k) accounts in 2027, with the biggest opportunities going to workers approaching retirement.
The Internal Revenue Service has announced new contribution limits that will allow some workers to save as much as $37,250 of their own money in a workplace retirement plan next year. With employer contributions and certain additional deposits, the maximum could reach $86,750. However, the changes also introduce an important consideration for higher-income workers, who may be required to pay taxes upfront on some retirement contributions.
How Much Can You Contribute to Your 401(k) in 2027?
The IRS announced Thursday, November 12, that the annual employee contribution limit for 401(k) plans will increase from $24,500 in 2026 to $25,500 in 2027. The new limit also applies to 403(b) retirement plans, governmental 457 plans and the federal government’s Thrift Savings Plan.
Workers who are at least 50 years old by the end of 2027 can contribute additional money through special catch-up provisions designed to help Americans strengthen their retirement savings later in their careers. Those catch-up allowances are also increasing.
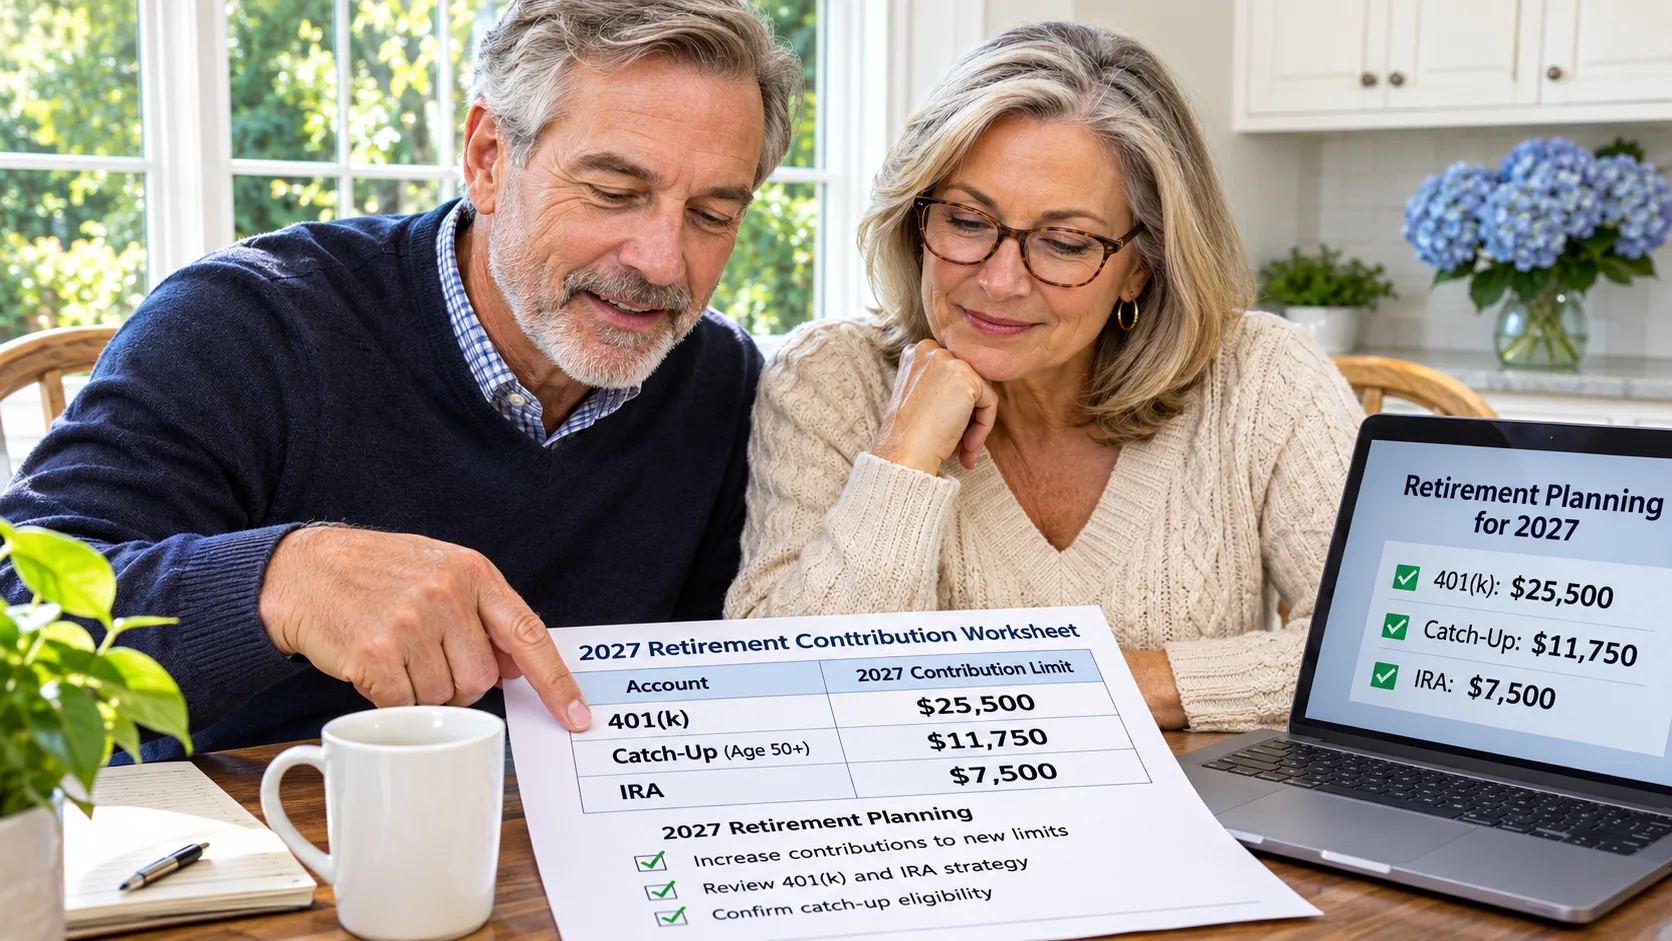
Here is how the new limits compare with 2026:
| Retirement Contribution | 2026 Limit | 2027 Limit |
|---|---|---|
| 401(k) base contribution | $24,500 | $25,500 |
| 401(k) catch-up, ages 50–59 and 64+ | $8,000 | $8,500 |
| 401(k) catch-up, ages 60–63 | $11,250 | $11,750 |
| IRA base contribution | $7,500 | $7,500 |
| IRA catch-up, ages 50+ | $1,100 | $1,100 |
| Total 401(k) employee contribution, ages 50–59 and 64+ | $32,500 | $34,000 |
| Total 401(k) employee contribution, ages 60–63 | $35,750 | $37,250 |
For workers in their early 60s, the increase could provide another opportunity to build savings during the final years before retirement. For some households, the financial impact could be substantial.
Workers Ages 60 to 63 Get an Especially Valuable Opportunity
One of the most significant provisions affects Americans between ages 60 and 63. Under the SECURE 2.0 retirement law, workers in this age group qualify for a higher catch-up contribution limit than other older employees.
In 2027, that additional allowance will rise to $11,750. Combined with the regular $25,500 limit, eligible workers can contribute $37,250 annually to their workplace retirement accounts, or approximately $3,104 per month.
For a married couple in which both spouses are between 60 and 63 and have eligible workplace retirement plans, combined employee contributions could reach $74,500 in one year. The ability to make these contributions depends on each spouse having sufficient eligible compensation and participating in a plan that permits the additional deposits.
Why the Final Years Before Retirement Matter
Americans approaching retirement often find themselves in a different financial position than they were earlier in life. Mortgages may be smaller or paid off, children may have completed college, and household expenses may be more manageable. For some, these changes create an opportunity to redirect more income toward retirement.
Additional contributions made during these years can also benefit from investment growth, although the amount accumulated will depend on market performance and when withdrawals begin. For someone who has fallen behind on retirement savings, the higher limits provide additional room to catch up.
Some Savers Could Put as Much as $86,750 Into Their 401(k)
The $37,250 employee contribution ceiling is only part of the picture. The IRS also increased the overall annual contribution limit for defined contribution retirement plans to $75,000 in 2027, up from $72,000 in 2026.
This broader limit can include employee salary deferrals, employer matching contributions, employer profit-sharing contributions and certain additional after-tax employee contributions. For eligible workers ages 60 to 63, the $11,750 super catch-up allowance can be added above that $75,000 ceiling, creating a potential combined annual contribution of $86,750.
However, most workers will never reach that amount. Doing so generally requires substantial income and a retirement plan that permits the necessary combination of employer and employee contributions.
The headline figure is particularly relevant for higher-income professionals, executives and employees participating in retirement plans with additional contribution features. It also highlights an important distinction: The amount an employee can personally defer from regular compensation is considerably lower than the maximum amount that can enter the account from all permitted sources.
A New Tax Rule Could Affect Higher-Income Workers
One of the most important retirement planning considerations for 2027 involves how catch-up contributions are taxed.
Under rules established by SECURE 2.0, employees whose wages from their current employer exceeded a specified threshold during the previous year generally must make their catch-up contributions on a Roth basis. For 2027, that threshold is more than $155,000 in applicable 2026 wages.
This means affected workers who want to make additional catch-up contributions in 2027 generally must direct those dollars into a Roth 401(k), rather than make them as traditional pretax contributions.
Why This Matters
Traditional 401(k) contributions generally reduce taxable income in the year they are made, with taxes paid when the money is withdrawn during retirement. Roth 401(k) contributions, by comparison, are made with after-tax dollars, allowing qualified withdrawals during retirement, including associated investment earnings, to be tax-free.
For higher-income workers, the Roth catch-up requirement could mean a larger current income tax bill than they would have faced if those contributions were made pretax. Over time, however, building additional Roth savings may provide greater flexibility when managing taxable retirement income.
Importantly, the requirement generally applies to catch-up contributions. Eligible employees may still have the option to make their regular 401(k) salary deferrals on a pretax basis.
Workers approaching the $155,000 threshold should review their 2026 wages and confirm how their employer’s retirement plan will handle catch-up contributions in 2027.
IRA Contribution Limits Are Staying the Same
While workplace retirement plans are receiving higher contribution limits, Americans saving through traditional and Roth IRAs will see no increase in their basic annual allowances.
For 2027, the IRA contribution limit remains $7,500. Workers ages 50 and older can contribute an additional $1,100, bringing their total potential annual IRA contribution to $8,600.
The IRS adjusts retirement contribution limits using inflation-based formulas. IRA limits typically increase in $500 increments, and inflation was insufficient to produce another increase for 2027.
However, the agency did make changes to income thresholds governing who can contribute directly to a Roth IRA.
For 2027, the Roth IRA income phase-out ranges will be:
- Single filers: $158,000 to $173,000.
- Married couples filing jointly: $250,000 to $260,000.
Taxpayers with modified adjusted gross income above those ranges generally cannot make direct Roth IRA contributions. Those within the ranges may qualify for reduced contributions.
Traditional IRA deduction limits are also subject to income-based restrictions when the taxpayer or their spouse participates in a workplace retirement plan. This makes it important to distinguish between being allowed to contribute to an IRA and being eligible to deduct that contribution.
The Retirement Savings Mistake That Could Cost Workers Thousands
The new contribution limits create an opportunity, but taking advantage of them requires action.
Many employees set their 401(k) contribution percentage when they enroll in their employer’s plan and rarely revisit it. Others increase contributions automatically each year but may still remain well below the amounts they are permitted to save.
For a worker earning $120,000 annually, for example, an increase from a 10% contribution rate to 12% would redirect an additional $2,400 into retirement savings each year. That money could potentially grow over time, depending on investment performance.
Another common oversight involves employer matching contributions. If a company offers matching retirement contributions, employees should understand how much they need to contribute to receive the full available match. Failing to contribute enough could mean missing out on employer-provided retirement benefits.
Maximizing Your Contribution Is Not Always the Best First Move
There is also a practical limitation to the IRS increases. A higher legal contribution limit does not automatically mean every household should direct the maximum possible amount into retirement accounts.
Workers carrying high-interest debt, lacking emergency savings or expecting large near-term expenses may need to balance competing financial priorities. For older Americans, the decision also depends on how close they are to retirement, when they expect to begin withdrawing funds and how much financial flexibility they need.
The goal is to use the available retirement benefits strategically while maintaining a sustainable household budget.
Three Steps to Take Before January 2027
Americans who want to benefit from the increased contribution limits should consider reviewing their retirement plans before the new year begins.
1. Recalculate your 401(k) contribution rate.
Determine how much you can comfortably contribute in 2027 and whether your current payroll deduction will reach that goal. Employees hoping to maximize contributions should calculate the amount needed across their expected pay periods.
2. Check your eligibility for catch-up contributions.
Workers turning 50 during 2027 may qualify for the standard catch-up allowance, while those reaching ages 60 through 63 may qualify for the larger amount. Confirm your employer’s plan supports the relevant contributions.
3. Review the tax treatment of your contributions.
Higher-income workers should confirm whether the Roth catch-up requirement applies. Others may want to consider how traditional and Roth contributions fit into their longer-term retirement and tax planning.
Employees should also verify whether their employer matches contributions throughout the year or provides a year-end true-up. Reaching the annual employee limit too early can affect matching contributions under some plan designs.
What the New Limits Mean for Your Retirement
The IRS increases will give millions of Americans additional room to save through workplace retirement plans in 2027. For younger workers, the new $25,500 limit offers another opportunity to build wealth over several decades, while Americans over 50 will benefit from larger catch-up allowances during a period when retirement decisions often become more urgent.
For workers ages 60 to 63, the ability to contribute as much as $37,250 personally, or potentially $86,750 when qualifying employer and additional contributions are included, represents a particularly valuable planning opportunity.
The most important decision may be made well before 2027 begins. Reviewing retirement contributions now could help ensure that additional savings opportunities are not overlooked when the new limits take effect on January 1.
About Author