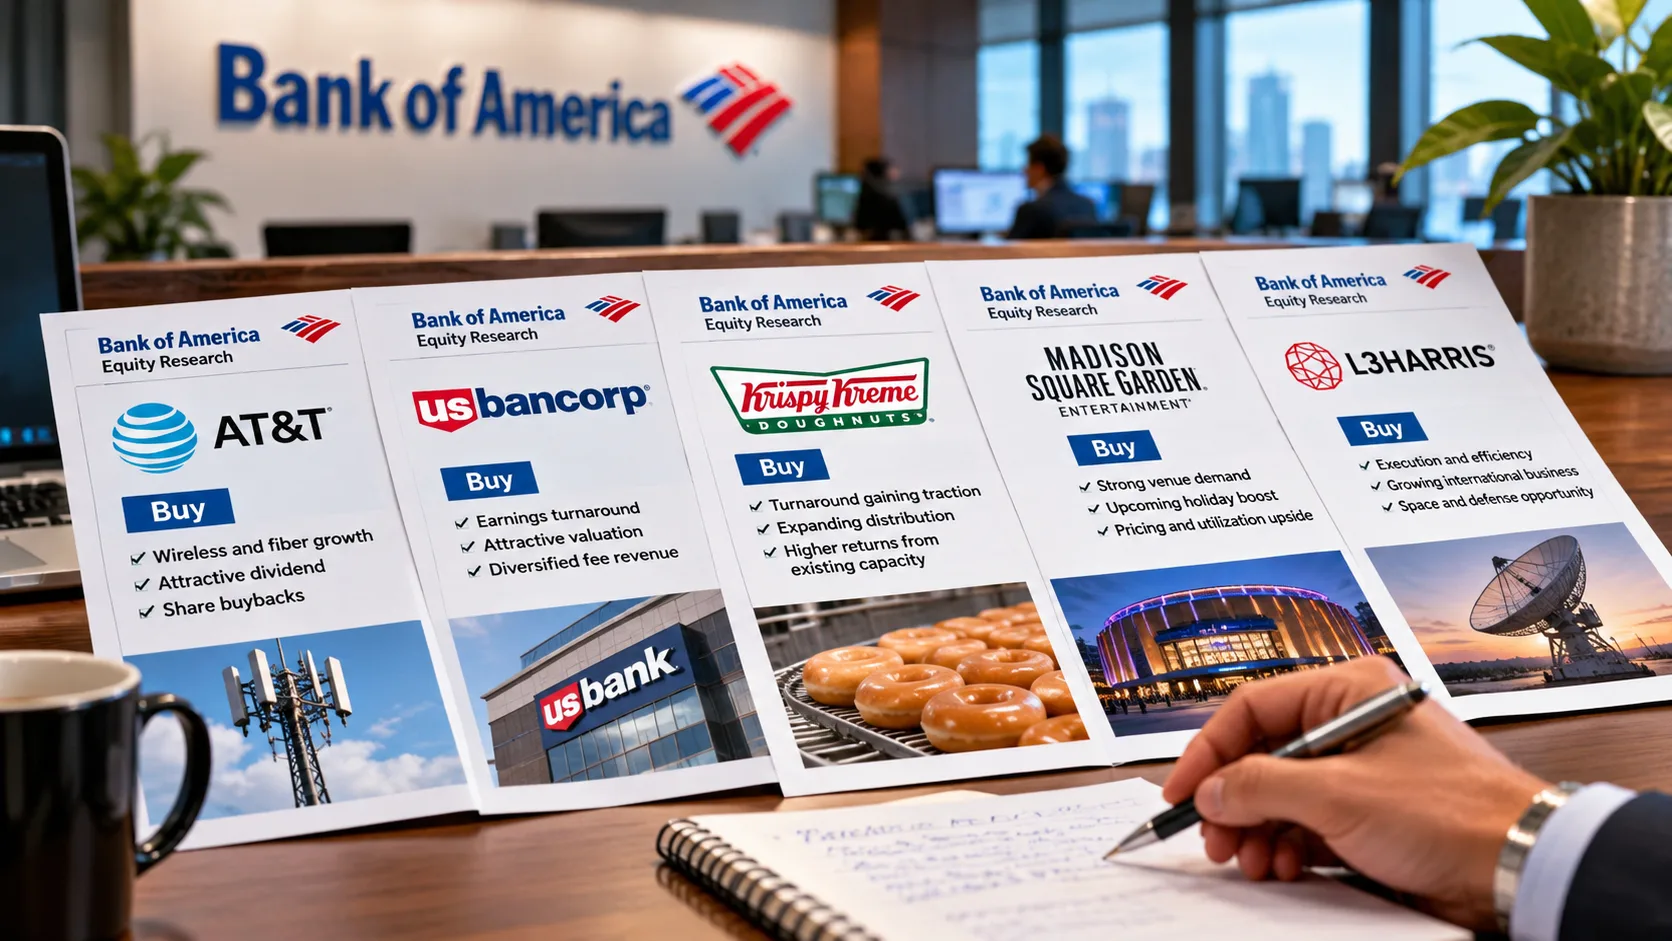
Even with the market facing continued uncertainty, Bank of America says investors still have opportunities to find stocks with meaningful upside. The firm sees potential in a mix of companies across telecom, banking, defense, entertainment and consumer retail, arguing that strong fundamentals and company-specific catalysts could help these names outperform even if broader market sentiment stays uneasy.
The call stands out because it is not centered on the usual mega-cap technology trade. Instead, Bank of America is pointing investors toward companies that could benefit from improving cash flow, earnings growth, operational momentum or undervalued business assets. Its bullish list includes AT&T, U.S. Bancorp, Krispy Kreme, Madison Square Garden Entertainment and L3Harris Technologies.
Where Bank of America Sees Opportunity
Market volatility has made many investors more selective, with money often flowing toward companies that can generate dependable earnings and hold up reasonably well during uncertain periods. Bank of America’s latest picks reflect that mindset, but they also show that safety and upside do not have to be mutually exclusive.
Some of the names on the list offer defensive characteristics, including recurring revenue or exposure to sectors with relatively stable demand. Others are more turnaround-oriented, where the upside depends on management execution, cost discipline and catalysts that could improve investor confidence. That mix gives the list broad appeal, though the risks are very different from one company to the next.
AT&T Remains Bank of America’s Top Telecom Pick
Bank of America reiterated its Buy rating on AT&T and called it its top U.S. telecom stock pick after better-than-expected third-quarter 2026 results. The firm cited AT&T’s combination of wireless and fixed-line assets, a balanced approach to subscriber growth and profitability, attractive dividend yield, share repurchase program and improving free cash flow and earnings-per-share growth.
That matters because AT&T’s investment case is no longer just about being a legacy telecom giant with a dividend. The company has been working to reposition itself around stronger operating performance, particularly through wireless execution and fiber expansion. If it can continue improving free cash flow while returning capital to shareholders, that could make the stock appealing to investors looking for both income and moderate upside.
In a market where many investors are looking for durability, AT&T’s recurring customer revenue and improving cash generation may help it stand out. The key question is whether management can sustain that momentum while remaining competitive in an industry that still requires heavy capital investment.
U.S. Bancorp Could Benefit From an Early-Stage Turnaround
Bank of America also remains constructive on U.S. Bancorp, arguing that the bank’s valuation still looks compelling given its earnings outlook. The firm highlighted that the stock trades at about 9.7 times estimated 2027 earnings, while average annual earnings-per-share growth is expected to run around 10% in fiscal 2027 and 2028. It also pointed to the company’s 1.7 times projected year-end 2027 tangible book value and 18% return on tangible common equity.
The bull case here is centered on a turnaround that may still be in its early innings. Bank of America expects U.S. Bancorp to benefit from fixed asset repricing and diversified fee revenue streams, while management continues working toward positive operating leverage. In practical terms, that means investors could see a combination of rising profitability and a stock valuation that still does not fully reflect the company’s earnings potential.
For investors, bank turnarounds can be especially powerful when expectations are low and the earnings recovery becomes more visible over time. If U.S. Bancorp delivers the kind of double-digit earnings growth Bank of America expects, the stock could have room to re-rate higher.
Krispy Kreme’s Turnaround Story Is Gaining Credibility
Krispy Kreme may be one of the more surprising names on the list, but Bank of America sees several positive catalysts ahead. Analyst Sara Senatore said the firm came away from the company’s latest earnings report more confident despite continued consumer headwinds.
A major part of that optimism stems from the company holding its fiscal 2026 adjusted EBITDA guidance even though edible oils and fuel costs have moved higher since the second quarter. Bank of America said that was one of the clearest signs yet that Krispy Kreme’s turnaround savings appear durable.
The firm also pointed to continued growth in Krispy Kreme’s Fresh Delivery service, which expands distribution by bringing products into grocery and retail stores. That matters because it creates another path for growth beyond traditional standalone stores and could help the company leverage its existing production capacity more effectively.
Bank of America said its Buy rating is supported by Krispy Kreme’s distinctive product offering, its ability to drive better returns from existing infrastructure and its long-term opportunity to expand U.S. and Canada access points to 15,000. With the stock already up sharply this month, investors are clearly starting to notice, but Bank of America believes there could still be more upside if execution continues to improve.
Madison Square Garden Entertainment Has More Than One Growth Driver
Madison Square Garden Entertainment is another name Bank of America believes still has momentum, even after a strong run. The company recently delivered another solid earnings report, helped in part by the impact of Harry Styles performances. However, Bank of America said the bigger takeaway is that the quarter reinforced the earnings power of the company’s irreplaceable venue portfolio.
That is an important distinction. While a major artist can certainly provide a short-term boost, the broader story is about the long-term value of owning premier live entertainment venues that can benefit from utilization, pricing power and ancillary spending. Those assets are difficult to replicate, and in a healthy consumer environment they can become highly productive earnings engines.
The bank also sees another catalyst on the horizon through the Christmas Spectacular. With 231 planned shows compared with 215 last year, and advance ticket revenue running ahead of pace, the holiday season could provide another meaningful lift. After shares have already climbed 48% this year, the stock is no longer under the radar, but Bank of America still sees room for additional upside if the company continues delivering.
L3Harris Is Positioned Around Defense Strength and Better Execution
Bank of America’s bullish stance on L3Harris Technologies reflects both company-specific and sector-wide factors. Analyst Ronald Epstein said he recently met with the defense company’s new chief executive and came away more constructive on the stock.
According to Epstein, the CEO outlined three clear priorities: improve and optimize execution, grow the international business, which currently accounts for 24% of revenue, and avoid transformational mergers and acquisitions. That message appears to have resonated with Bank of America, which also said it likes L3Harris’ broad portfolio and sees the company as well positioned to participate in the space sector.
For investors, this story is as much about discipline as it is about opportunity. Defense companies can benefit from long-cycle government demand and geopolitical tailwinds, but better execution is often what separates steady compounders from disappointing operators. If the new management team can improve performance while expanding internationally and staying selective on dealmaking, Bank of America believes investors will respond favorably.
The stock has already been moving in the right direction, climbing in five of the last six weeks and gaining nearly 5% over the last five days alone. That momentum may continue if investors increasingly view L3Harris as a cleaner, more focused defense name with room for multiple expansion.
What This Means for Investors
What stands out about Bank of America’s list is the diversity of the opportunity set. These are not five stocks driven by the same macro trend. AT&T is more about income, stability and cash flow. U.S. Bancorp offers a banking turnaround tied to earnings growth and valuation. Krispy Kreme is a consumer turnaround story. Madison Square Garden Entertainment is a play on live-event demand and venue economics. L3Harris offers exposure to defense spending and operational improvement.
That mix could be especially appealing in a market where investors are trying to stay selective rather than simply chasing momentum. If uncertainty remains elevated, stocks with company-specific catalysts and improving fundamentals may have a better chance of outperforming than names that rely purely on multiple expansion.
At the same time, investors should remember that upside cases only work if execution follows. A bullish analyst call can help draw attention to a stock, but future returns will depend on whether these companies deliver the earnings, cash flow and strategic progress Bank of America expects.
The Bottom Line
Bank of America’s latest stock picks suggest there are still attractive opportunities hiding in plain sight, even in a market that feels unsettled. The firm’s five favored names each offer a different path to upside, whether through stronger cash flow, improving earnings, operational turnarounds or unique business assets.
For investors willing to look beyond the market’s biggest and most crowded trades, that could be the more important takeaway. In a nervous market, the next winners may come from companies quietly getting their fundamentals right.
About Author