Millions of Americans could face a substantial reduction in Social Security benefits within six years unless Congress takes action to address the program’s growing financial shortfall. The latest government projections show that retirement and survivor benefits could be reduced by approximately 22% beginning in 2032, potentially costing the average retiree hundreds of dollars per month.
With the November 3 midterm elections approaching, the next Congress will inherit one of the most consequential financial challenges facing American retirees. The decisions lawmakers make could determine whether benefits remain intact, payroll taxes increase or future retirees face changes to the program they have spent decades paying into.
Social Security’s Retirement Fund Could Run Short in 2032
The Social Security Administration’s 2026 Trustees Report projects that the Old-Age and Survivors Insurance (OASI) Trust Fund will exhaust its reserves in the fourth quarter of 2032, several months earlier than previously anticipated.
At that point, continuing payroll tax revenue and other program income would be sufficient to cover approximately 78% of scheduled retirement and survivor benefits. Unless Congress changes the law, the program would lack the resources needed to pay the remaining 22%.
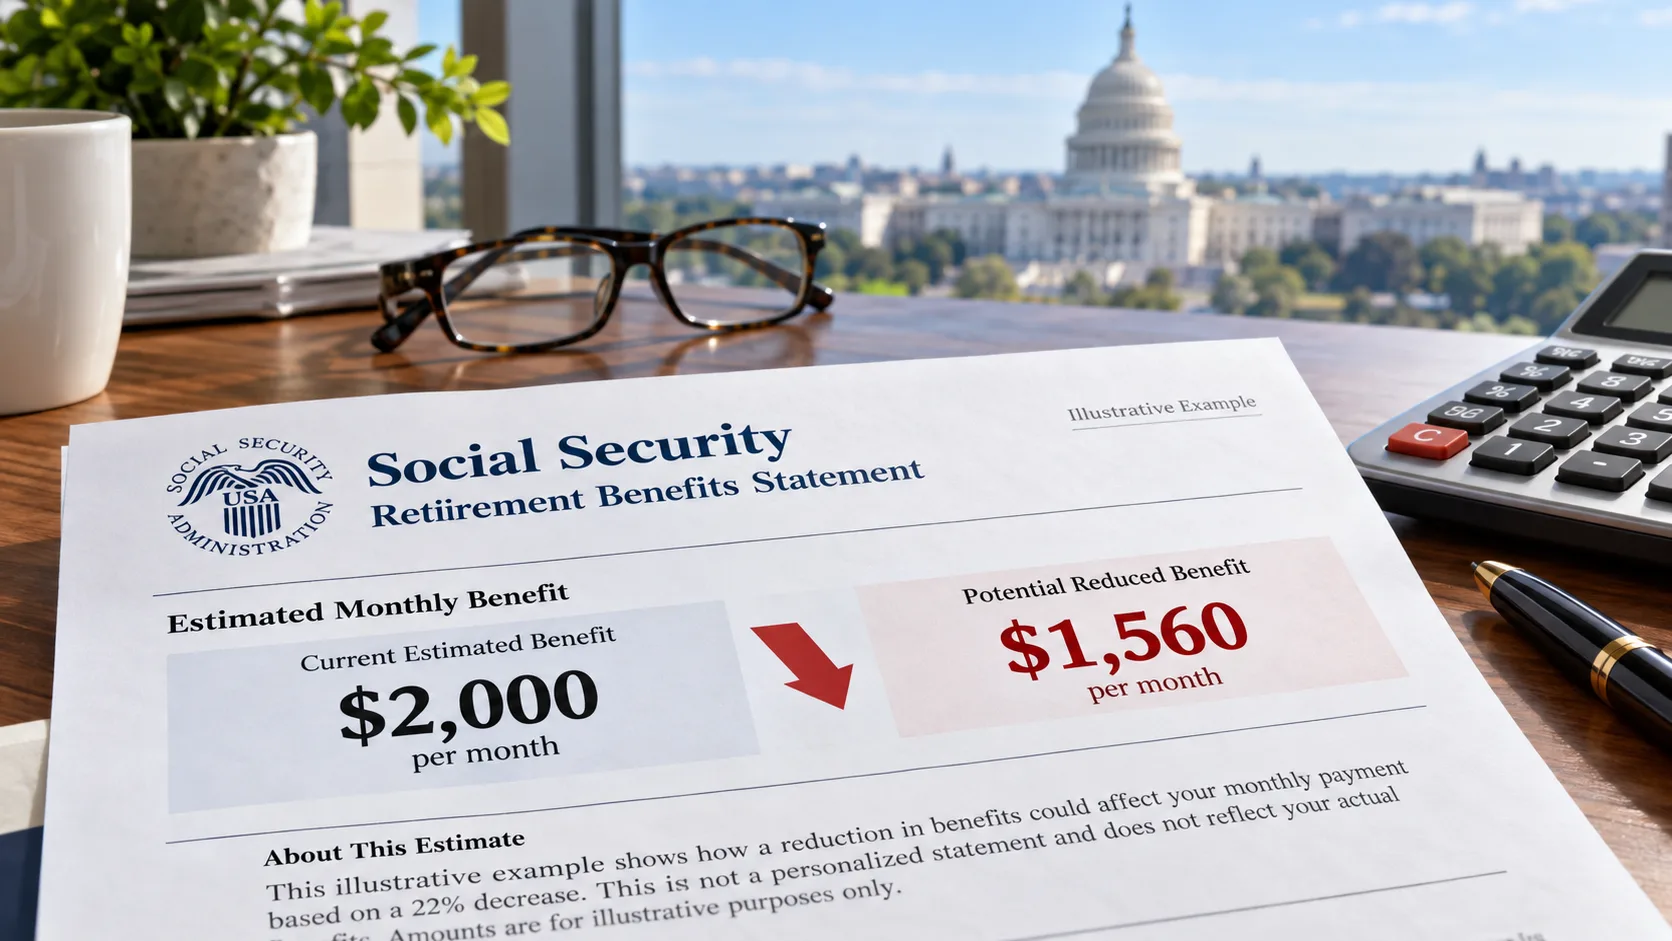
For someone expecting $2,000 per month in Social Security benefits, a 22% reduction would mean receiving approximately $1,560 instead. That’s a loss of $440 per month, or $5,280 annually.
A retiree expecting $3,000 per month could face a reduction of approximately $660, lowering annual income by nearly $8,000.
These are illustrative calculations based on the projected funding shortfall, rather than announced reductions to individual benefit payments. No such cuts have been approved, and Congress has several options for preventing them.
The outlook is somewhat different when Social Security’s retirement and disability programs are considered together. The Trustees project that their combined reserves would last until 2034, when continuing income could cover approximately 83% of scheduled benefits. The two funds are legally separate, however, and combining their resources would require legislative action.
Why Social Security’s Financial Problems Are Getting Worse
Social Security is primarily financed through payroll taxes collected from workers and employers. As Americans earn wages, a portion of their income goes toward supporting current retirees and other eligible beneficiaries.
For decades, the program collected more than it paid out, allowing it to accumulate reserves in special Treasury securities. Those reserves are now being drawn down as benefit payments exceed incoming revenue.
The underlying problem is demographic.
Americans are living longer, while birth rates have declined and the number of workers supporting each beneficiary has fallen substantially. In 1960, there were more than five workers paying into Social Security for every beneficiary. Today, that ratio is approximately 2.9 workers per beneficiary.
The ratio is projected to decline further in the coming decades, increasing the financial pressure on the program.
The latest Trustees Report also incorporated revised assumptions about fertility and immigration, both of which affect the future workforce and payroll tax collections. Those changes contributed to a worsening long-term financial outlook.
In 2025, Social Security collected approximately $1.45 trillion in total income while spending about $1.61 trillion. The difference was covered by drawing down accumulated trust fund reserves, which declined by approximately $160 billion during the year.
The Trustees estimate that Social Security’s long-term funding shortfall has increased substantially compared with last year’s projections.
Without changes to taxes, benefits or other program rules, the imbalance will continue to grow.
Why the Upcoming Election Matters for Retirees
The November 3 midterm elections will determine the composition of Congress at a time when Social Security’s financial challenges are becoming increasingly difficult to postpone.
Although the projected depletion of the retirement trust fund remains several years away, major reforms can take time to negotiate and implement. Changes affecting payroll taxes, retirement ages or benefit formulas may also require transition periods to avoid disrupting Americans who are already approaching retirement.
The next Congress could begin developing a long-term solution, although the outcome will depend on negotiations between lawmakers and the White House.
Social Security has historically been one of the most politically sensitive federal programs. Millions of older Americans depend on its monthly payments, making proposals to reduce benefits or raise taxes difficult for politicians in both parties.
The last major bipartisan overhaul occurred in 1983, when Congress approved a combination of tax increases, changes to benefits and a gradual increase in the full retirement age.
Those reforms strengthened Social Security’s finances for decades, but demographic and economic changes have created another substantial funding gap.
The challenge facing today’s lawmakers is finding an approach that preserves retirement security while maintaining the program’s long-term financial sustainability.
Lawmakers Have Several Options, but Every One Has a Cost
Congress could address Social Security’s projected shortfall through higher revenue, changes to benefits or some combination of both.
One frequently discussed proposal involves increasing the amount of income subject to Social Security payroll taxes.
In 2026, workers pay Social Security tax on earnings up to $184,500. Income above that amount is generally exempt from the program’s 12.4% payroll tax, which is split between employees and employers.
Raising or eliminating the taxable wage ceiling would increase contributions from higher-income workers and could generate substantial additional revenue. However, the financial impact would depend on how the proposal is structured, including whether additional contributions would generate higher future benefits.
Another possibility involves gradually increasing the full retirement age.
Under current law, the full retirement age is 67 for people born in 1960 or later. Some policymakers have suggested raising that age further to reflect longer life expectancy.
Such a change would effectively reduce lifetime benefits for many future retirees, particularly those who claim benefits before reaching the higher retirement age. It could also place additional pressure on Americans whose health or occupations make working longer difficult.
Lawmakers could instead adjust how future benefits are calculated, modify cost-of-living adjustments or increase payroll tax rates.
Each approach has different consequences for workers, retirees, employers and the federal government’s finances.
There is also the possibility of combining smaller changes across several areas, spreading the financial impact rather than relying on a single major adjustment.
Why Some Estimates Mention Benefit Cuts as High as 26%
Different Social Security projections have produced different estimates of the potential benefit reductions needed to address the program’s finances.
The 2026 Trustees Report indicates that the retirement and survivor trust fund could have enough continuing income to pay approximately 78% of scheduled benefits when its reserves are depleted in 2032. That produces the projected 22% shortfall.
However, a separate long-term solvency calculation considers how much benefits would need to be reduced immediately to keep the program financially balanced over the next 75 years without increasing revenue.
According to an analysis by the Congressional Research Service, an immediate across-the-board benefit reduction of approximately 25.2% would be one hypothetical way to restore long-term solvency under the 2026 projections.
Waiting until 2034 to address the combined program’s financing gap would require even larger hypothetical adjustments if lawmakers relied entirely on reducing benefits.
These calculations describe different funding scenarios. They should not be interpreted as separate benefit cuts that have already been scheduled or approved.
The key point is that delaying action can make the eventual financial adjustments more difficult, particularly if policymakers want to protect current beneficiaries and people approaching retirement.
What a 22% Reduction Would Mean for Retirement Planning
Social Security remains a central source of income for millions of older Americans, including households that have limited savings or no traditional pension.
A reduction of several hundred dollars per month could force some retirees to reconsider spending on housing, transportation, healthcare and other essentials.
For retirees with substantial investment portfolios, lower Social Security payments could create a different challenge: the need to withdraw more money from retirement accounts.
Consider someone who receives $30,000 annually from Social Security and withdraws another $20,000 from savings to cover expenses.
A 22% reduction in Social Security would reduce annual benefits by $6,600. Maintaining the same spending level would require increasing withdrawals from $20,000 to $26,600, assuming no other income or spending changes.
That represents a 33% increase in the amount withdrawn from investments.
Over time, larger withdrawals can place additional pressure on retirement portfolios, particularly during periods of stock-market declines. Selling investments to cover living expenses during a downturn can also reduce the assets available to benefit from a future market recovery.
The risk is especially important for people approaching retirement who may have fewer working years available to increase their savings.
At the same time, retirees should avoid making drastic financial decisions based solely on these projections. Congress has time to address the shortfall, and any eventual legislation could produce a substantially different outcome.
The Biggest Risk May Be for Americans Approaching Retirement
Workers currently in their 50s and early 60s face a particularly complicated planning environment.
Many have spent decades contributing to Social Security and are approaching the point when their monthly benefits will become an important part of household income.
However, they may retire close to the period when the retirement trust fund is projected to exhaust its reserves.
For these households, uncertainty about future benefits can affect decisions about when to retire, when to claim Social Security and how much to save during their remaining working years.
Delaying benefits beyond full retirement age can increase an individual’s monthly payment, generally up to age 70. That may provide additional financial flexibility for some households, although the best claiming age depends on health, income needs, marital circumstances and other factors.
Importantly, delaying a claim does not eliminate the broader risk of a future funding shortfall. Any legislated changes to benefits would depend on the specific rules Congress adopts.
Workers approaching retirement should consider reviewing their estimated Social Security benefits alongside their retirement savings, expected expenses and other sources of income.
Three Practical Steps Retirees Can Take Now
The uncertainty surrounding Social Security’s finances does not mean retirees need to assume the worst outcome will occur. However, it does provide a reason to examine how dependent their financial plans are on future government benefits.
First, calculate how much of your retirement income comes from Social Security. Someone receiving 70% of household income from the program faces a different level of exposure than someone receiving 25%. Understanding that dependence can help identify how vulnerable a household might be to future policy changes.
Second, review a more conservative retirement-income scenario. Financial plans can be tested using lower projected Social Security payments, even when no reduction is currently scheduled. This can help households determine whether their savings, pensions or other income sources provide enough flexibility to absorb unexpected changes.
Third, follow actual legislative proposals rather than campaign promises alone. Broad statements about protecting Social Security provide limited information about how lawmakers intend to finance the program. Specific legislation involving payroll taxes, benefit formulas, retirement ages or trust fund financing will offer a clearer picture of the potential consequences.
Investors should also consider how changes to Social Security could affect their broader financial plans. Higher payroll taxes could influence take-home pay during working years, while changes to retirement benefits could alter future withdrawal needs.
The Next Congress Faces a Difficult Decision
The 2026 Trustees Report provides one of the clearest warnings yet about the financial challenges facing Social Security.
The retirement trust fund is projected to exhaust its reserves in 2032, potentially leaving the program unable to pay approximately 22% of scheduled retirement and survivor benefits unless Congress intervenes.
The next Congress will have the opportunity to begin addressing that shortfall, but lawmakers face difficult choices involving taxes, retirement ages and future benefit payments.
The longer those decisions are postponed, the fewer options policymakers may have for spreading the financial impact over time.
For retirees and Americans approaching retirement, Social Security benefits remain payable under current law, and no across-the-board reductions have been approved.
Still, the latest projections illustrate why the program’s financial future deserves close attention. With millions of Americans relying on Social Security for financial stability, the decisions made in Washington over the coming years could have lasting consequences for retirement income across the country.
About Author