Wall Street sees buying opportunities in five stocks heading into earnings season, including three that have suffered double-digit declines this year. Bank of America believes their next earnings reports and upcoming business developments could give investors reasons to reconsider.
With investors increasingly questioning expensive valuations, artificial intelligence spending and the durability of corporate earnings, Bank of America is identifying stocks it believes could outperform despite recent market weakness.
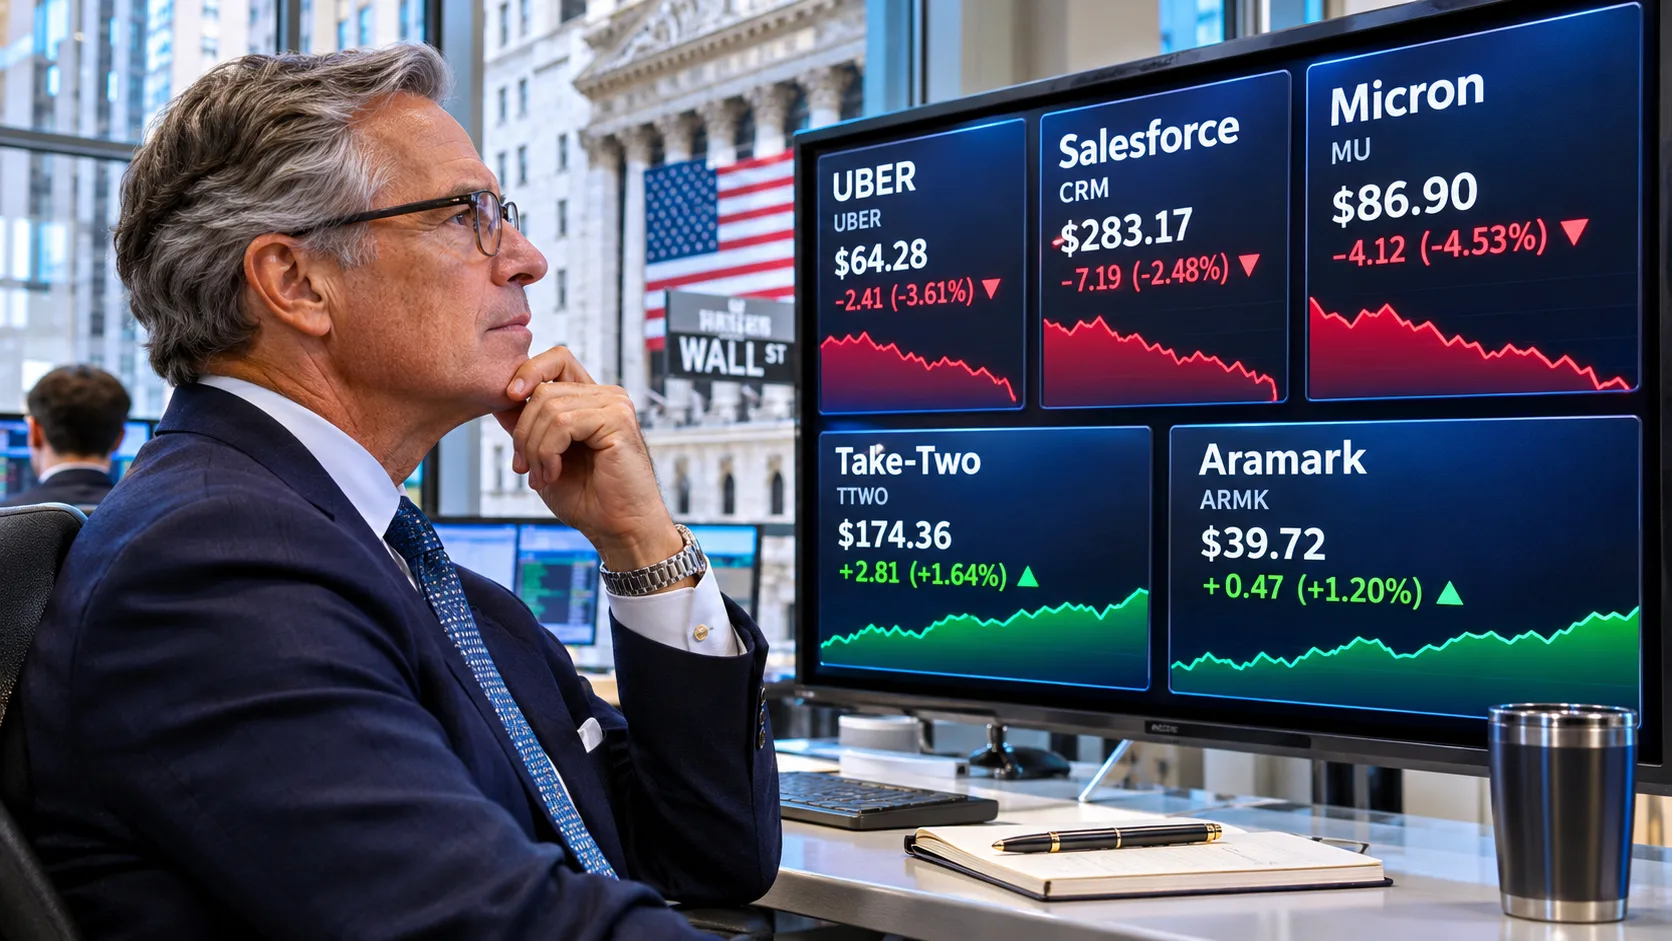
The investment bank has highlighted five buy-rated companies: Uber Technologies, Take-Two Interactive, Salesforce, Micron Technology and Aramark. Each offers a different potential catalyst, ranging from autonomous vehicles and artificial intelligence to the highly anticipated release of Grand Theft Auto VI.
Several have experienced substantial selling pressure. According to the bank’s recent analysis, Take-Two shares have fallen approximately 25% in 2026, Uber is down about 20%, and Salesforce has declined roughly 13%.
Bank of America’s argument is that investors may be overlooking improving business fundamentals and future earnings potential. However, the upcoming reports will be critical in determining whether these stocks are genuinely undervalued or whether Wall Street’s concerns are justified.
Five Stocks Bank of America Believes Could Have More Room to Run
1. Uber Technologies (UBER): Down 20%, With Earnings Just Days Away
Uber is facing an important test on November 4, when the ride-sharing company reports third-quarter earnings.
Shares have fallen approximately 20% this year as investors question how the emergence of autonomous vehicles could reshape the ride-hailing industry. Competition from Alphabet-backed Waymo and Tesla’s robotaxi ambitions has raised concerns about Uber’s long-term market position.
Bank of America analyst Justin Post believes those concerns could create an opportunity.
The central question is whether Uber can establish itself as an essential distribution platform for autonomous vehicles, even as companies develop fleets that no longer require human drivers.
Uber already has an important partnership with Nvidia. The companies announced plans to introduce Nvidia-powered autonomous vehicles beginning in Los Angeles and San Francisco in 2027, with ambitions to expand into 28 cities globally by 2028.
Post believes additional clarity around Uber’s autonomous vehicle deployment plans could improve investor sentiment.
The company’s existing business also provides an important foundation. In the second quarter, Uber reported 22% year-over-year gross bookings growth on a constant-currency basis, while adjusted EBITDA increased 33%.
What investors should watch: The November 4 earnings call could provide new information about autonomous vehicle partnerships, deployment schedules and the economics of integrating driverless cars into Uber’s platform.
The biggest risk is that autonomous vehicle developers eventually gain enough scale to compete directly with Uber, potentially weakening its pricing power.
2. Take-Two Interactive (TTWO): Down 25% Ahead of a Major Gaming Launch
Take-Two Interactive has experienced one of the steepest declines among Bank of America’s selections, with shares down approximately 25% this year.
Yet the company is approaching what could become one of the most important product launches in video game history.
Grand Theft Auto VI is scheduled for release on November 19, just 10 days after Take-Two reports quarterly earnings on November 9.
Bank of America analyst Omar Dessouky believes investors should maintain exposure to Take-Two through the launch because the game’s long-term earnings potential could exceed current market expectations.
The opportunity extends beyond initial game sales. Grand Theft Auto Online has demonstrated how a successful gaming franchise can generate recurring revenue long after its original release.
A new online experience associated with GTA VI could create another substantial source of revenue through digital purchases and continuing player engagement.
Take-Two previously projected fiscal 2027 net bookings of $8 billion to $8.2 billion, reflecting expectations for a significant increase in business activity.
For investors, the important question is how much of that projected growth is already reflected in the stock price.
A successful launch could help justify higher future earnings estimates. However, expectations surrounding GTA VI are exceptionally high, leaving Take-Two exposed to disappointment if initial sales, launch timing or monetization fall short.
What investors should watch: Management’s November 9 earnings guidance, confirmation of the November 19 launch timetable and any additional information about GTA Online’s future.
Even if GTA VI becomes a commercial success, the stock’s immediate reaction will depend on how actual results compare with investor expectations.
3. Salesforce (CRM): Down 13% as Wall Street Reconsiders Its AI Potential
Salesforce has struggled to convince investors that artificial intelligence will meaningfully accelerate its growth.
Its shares are down approximately 13% this year, but Bank of America believes that weakness may be creating an attractive entry point.
Analyst Tal Liani recently upgraded Salesforce two levels, moving the stock from underperform to buy.
His argument centers on the company’s ability to incorporate artificial intelligence into software products that businesses already use.
Salesforce has an established position in customer relationship management, enterprise software and workplace collaboration through Slack. That existing customer base could provide an advantage as companies begin incorporating AI agents into their operations.
Rather than requiring businesses to replace their existing systems, Salesforce can introduce new AI capabilities into software that companies have already purchased and integrated into their workflows.
Bank of America is particularly encouraged by improving net new annual order value, an indicator of future contracted business, and accelerating momentum at Slack.
These developments could suggest that Salesforce is beginning to translate AI investment into measurable commercial demand.
For shareholders, the opportunity is straightforward: stronger subscription growth and improved profitability could support higher earnings expectations and a recovery in the stock’s valuation.
However, Salesforce faces significant competition from Microsoft, Oracle and other enterprise software providers introducing their own AI capabilities.
What investors should watch: Subscription revenue growth, new customer commitments, Slack performance and evidence that AI products are generating meaningful incremental revenue.
Investors will also want to see whether Salesforce can improve growth without sacrificing operating margins.
4. Micron Technology (MU): A Different Way to Invest in the AI Boom
While Nvidia has attracted enormous attention for its artificial intelligence processors, Bank of America sees a potentially compelling opportunity in another essential part of AI infrastructure: memory.
Micron Technology manufactures memory and storage products used in data centers, smartphones, computers and increasingly sophisticated AI systems.
The company is benefiting from growing demand for high-bandwidth memory, which helps advanced processors handle the enormous amounts of information required for AI workloads.
Bank of America analysts became more optimistic after meetings with Micron executives, including senior leaders responsible for operations, technology and finance.
The bank’s central thesis is that memory market conditions could become even tighter in 2027 and 2028 than in 2026.
That matters because memory pricing has historically been highly sensitive to the balance between supply and demand.
When supply becomes constrained, manufacturers can sometimes command higher prices, improving profitability. If demand continues increasing faster than production capacity, Micron could benefit from stronger pricing and higher-value products.
Micron’s September quarterly results already demonstrated the magnitude of the AI-driven memory expansion, with the company reporting record financial performance and projecting an even stronger fiscal 2027.
Still, memory chips have historically been cyclical products. Rapid increases in manufacturing capacity can eventually create excess supply, putting pressure on prices and profit margins.
What investors should watch: High-bandwidth memory demand, manufacturing capacity expansion, customer commitments and management’s expectations for memory pricing through 2027.
A major question is whether the current AI investment cycle will support structurally stronger profitability or eventually lead to another traditional semiconductor downturn.
5. Aramark (ARMK): A Less Obvious Growth Opportunity
Aramark may be the least recognizable name on Bank of America’s list for investors focused primarily on technology stocks.
The company provides food services and related operations to businesses, educational institutions, healthcare facilities and other organizations.
Bank of America sees potential for continued business expansion following operational changes introduced under a leadership transformation that began in 2019.
Those changes included strengthening sales capabilities, improving management incentives and placing greater emphasis on attracting new customers.
The bank believes Aramark can continue growing through new contracts, operational improvements and debt reduction.
Unlike the AI-driven businesses dominating much of Wall Street’s attention, Aramark operates in a more traditional sector where long-term service contracts and customer relationships can support recurring revenue.
The investment case depends on Aramark winning new business while improving profitability and reducing financial leverage.
If management delivers on those objectives, investors could become willing to assign the stock a higher valuation.
But the company also faces challenges, including labor expenses, food costs, contract competition and customer budget pressures.
What investors should watch: New contract wins, operating margins, revenue growth and progress toward reducing debt.
For investors concerned about excessive concentration in technology stocks, Aramark provides exposure to a different set of economic drivers.
Why Bank of America Is Looking at Stocks That Have Already Fallen
The most interesting aspect of Bank of America’s selections is the emphasis on companies whose share prices have declined despite identifiable growth opportunities.
Take-Two, Uber and Salesforce have all experienced double-digit losses in 2026, according to the bank’s analysis.
Those declines can create opportunities when investors have become too pessimistic about a company’s future. However, a lower share price does not automatically make a stock inexpensive.
The critical issue is whether earnings expectations have fallen by more or less than the stock price.
For example, a company whose shares decline 20% while its expected earnings remain stable may become more attractively valued. But if future profits are expected to fall by 30%, the stock could actually be more expensive relative to its earnings potential.
That distinction is especially important ahead of earnings announcements.
A company can exceed quarterly profit forecasts and still see its stock decline if management reduces future guidance. Conversely, a business reporting mediocre results can experience a sharp rally if its outlook proves better than investors feared.
Bank of America’s selections suggest the firm believes several companies have opportunities to deliver positive surprises through improving business fundamentals or more favorable forward guidance.
Three Different Investment Themes Could Drive the Next Move
Although these five companies operate in very different industries, their potential upside depends on three broad themes.
Artificial Intelligence Is Creating New Revenue Opportunities
Salesforce and Micron represent two distinct ways companies could benefit financially from AI.
Salesforce is attempting to monetize AI through software subscriptions and enterprise productivity tools. Micron benefits from demand for the physical infrastructure required to power increasingly sophisticated AI systems.
Both companies need to demonstrate that spending on artificial intelligence can translate into sustainable earnings growth.
Autonomous Vehicles Could Reshape Transportation Economics
Uber’s future increasingly depends on how autonomous vehicles change the economics of ride-hailing.
Driverless vehicles could eventually reduce certain operating costs and expand transportation availability. But these benefits will be divided among vehicle manufacturers, software developers, fleet operators and platforms connecting riders with transportation.
Uber’s ability to preserve its role in that ecosystem could become a major factor in its long-term valuation.
Company-Specific Catalysts Can Matter More Than the Broader Market
Take-Two and Aramark illustrate opportunities driven by events that are less directly connected to interest rates or the overall direction of technology stocks.
Take-Two faces a major product launch that could materially reshape its revenue outlook. Aramark’s opportunity depends on contract wins, operating performance and financial improvements.
These catalysts could allow individual companies to outperform even when broader stock market conditions remain uncertain.
Why Good Earnings May Still Fail to Lift These Stocks
One potential danger for investors is assuming that a positive earnings announcement will automatically produce a higher stock price.
Markets are forward-looking, and many investors position themselves ahead of major corporate announcements.
If a company’s stock has already rallied in anticipation of strong results, even excellent earnings may provide insufficient justification for additional gains.
Take-Two offers a particularly useful example. The tremendous excitement surrounding GTA VI could support long-term revenue growth, but a strong launch may already be reflected in analysts’ financial projections.
Salesforce faces a similar challenge. Investors may become more enthusiastic about its AI strategy, but expectations could rise faster than actual revenue.
Micron’s long-term prospects may also remain favorable even if its stock experiences volatility because investors question the sustainability of elevated memory prices.
This is why management guidance, future profit margins and the assumptions embedded in current valuations matter as much as quarterly earnings themselves.
The Earnings Dates and Catalysts Investors Should Circle
The immediate calendar offers several opportunities for investors to evaluate Bank of America’s investment arguments.
- November 4: Uber earnings. Investors will focus on operating performance and the company’s roadmap for autonomous vehicle partnerships.
- November 9: Take-Two earnings. Management’s guidance could influence expectations ahead of its major product launch.
- November 19: Grand Theft Auto VI scheduled release. The commercial debut could provide an early indication of whether Take-Two can meet its ambitious growth expectations.
- Upcoming Salesforce earnings: Investors will look for evidence that AI adoption is generating stronger recurring revenue and order growth.
- Upcoming Micron results and updates: Memory pricing, data center demand and capacity constraints will remain central to the company’s outlook.
- Aramark’s next operating update: Contract growth, profitability and financial leverage will help determine whether its turnaround continues.
These developments could produce meaningful price movements, particularly for companies where investor sentiment has already weakened.
The Takeaway for Investors
Bank of America’s five stock selections reflect a broader opportunity emerging across Wall Street: companies with promising long-term prospects are sometimes being sold because investors remain uncertain about their near-term performance.
Uber, Take-Two and Salesforce stand out because their stocks have already suffered significant declines, leaving room for a potential recovery if business results improve.
Micron offers exposure to the continuing expansion of artificial intelligence infrastructure, while Aramark provides a more traditional business transformation opportunity.
The common thread is that each company has a specific development capable of changing how investors value its future earnings.
For investors considering these stocks, the challenge is determining whether the market has already accounted for those catalysts or is still underestimating their potential.
With several major announcements approaching, the next few weeks could help determine which of Bank of America’s five selections represent genuine buying opportunities and which still face difficult challenges.
About Author