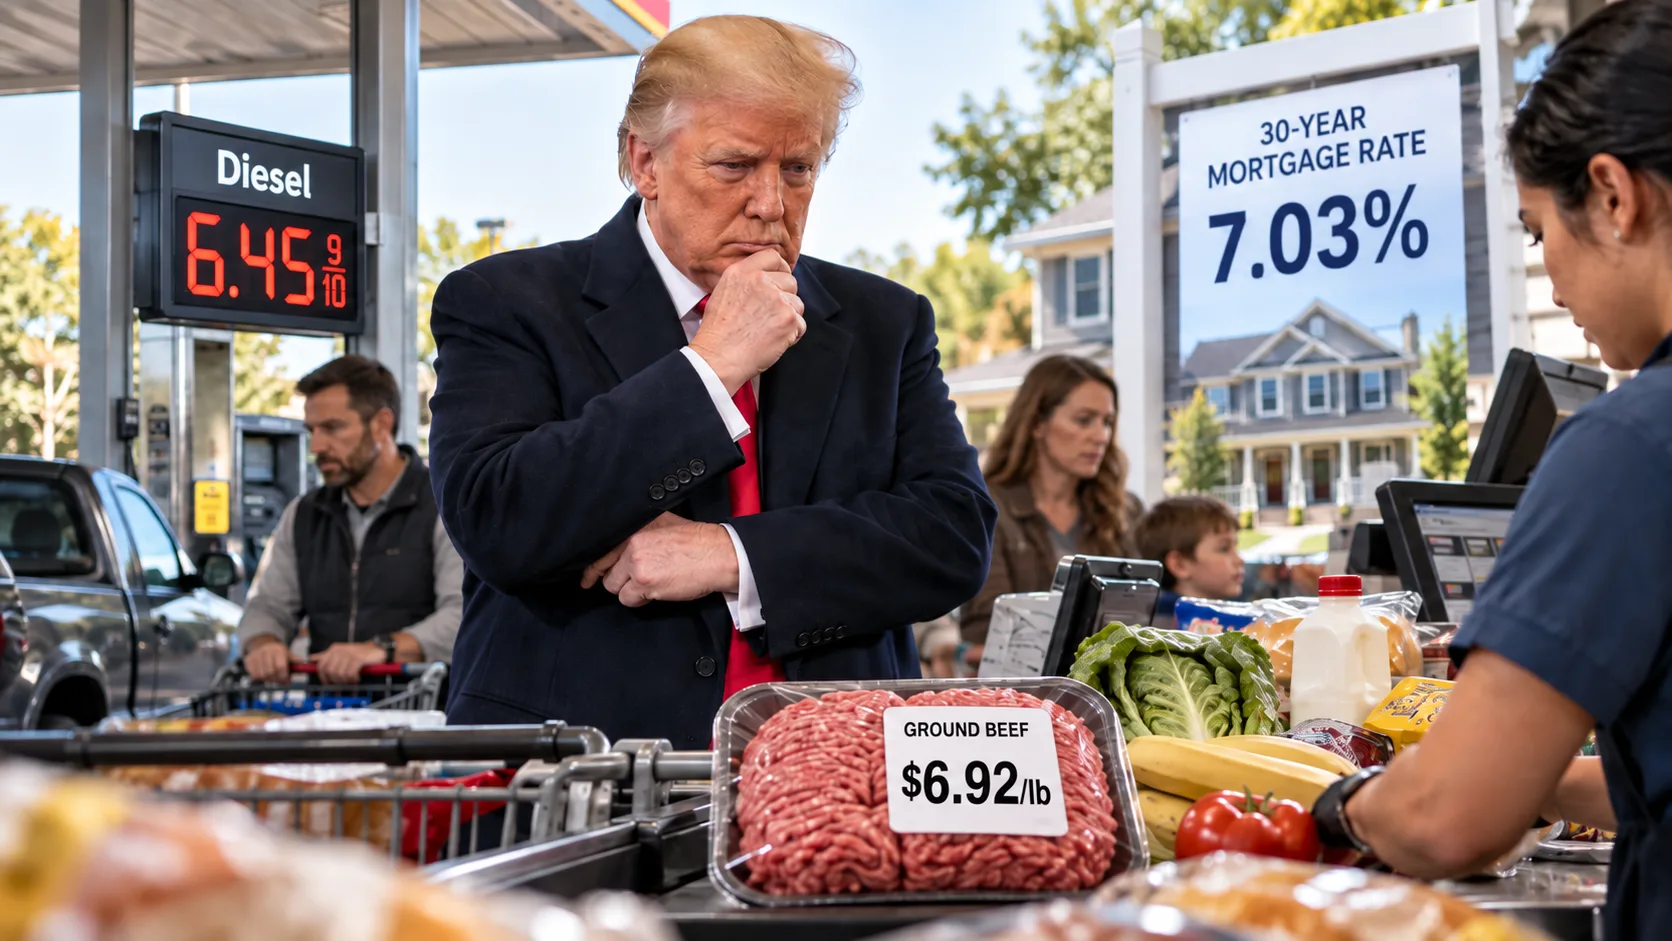
President Donald Trump is searching for ways to ease the affordability squeeze on American households, but nearly every proposal is colliding with another part of the economy.
Beef relief risks hurting ranchers. Restricting fuel exports could distort energy markets. A proposed $5,000 payment to American adults would require congressional action and could add enormous new spending power to an economy where inflation remains above the Federal Reserve’s target.
For investors, the bigger story is becoming clear: there may be no quick political fix for an affordability problem being driven at the same time by energy costs, interest rates, inflation and weak purchasing power.
Washington Is Taking Aim at Individual Prices
The administration has pursued or discussed several different approaches to affordability in recent weeks, often targeting one high-profile expense at a time.
In August, Trump expanded the amount of lean beef trimmings that can enter the United States under the lower tariff-rate quota. The additional quota totals 300,000 metric tons spread across three 30-day periods beginning September 1. The administration says increasing supply should help reduce pressure on ground beef prices.
The policy also illustrates the tradeoff facing Washington. More imported beef can increase supply for processors and consumers, but domestic cattle producers face more competition at a time when fuel, grain, fertilizer and other operating expenses remain elevated.
Energy presents an even harder problem. With diesel prices putting pressure on farmers, truckers and other businesses, some Republican lawmakers have called for restrictions on U.S. diesel exports. The administration has so far stopped short of adopting a mandatory export ban amid warnings from oil companies and administration officials that restricting exports could discourage production or create new supply distortions.
Then there is Trump’s biggest proposal. At the Republican midterm convention in Dallas on September 9, Trump proposed giving every adult American citizen a $5,000 “Trump Dividend” if Republicans retain control of both chambers of Congress in November.
Such a program would almost certainly require congressional approval. With roughly 270 million U.S. adults, a universal $5,000 payment could carry a gross price tag of roughly $1.35 trillion depending on eligibility and the final structure.
That immediately raises a difficult economic question: can Washington stimulate consumers without also stimulating prices?
The Affordability Problem Is Bigger Than Beef or Diesel
The latest inflation data helps explain why affordability remains so difficult to address.
Consumer prices rose 0.4% in August and were 3.4% higher than a year earlier. Gasoline alone jumped 3.9% during the month and accounted for more than one-third of August’s overall increase.
At the same time, workers are struggling to stay ahead. Average hourly earnings increased 3.1% from August 2025 through August 2026, while consumer prices increased 3.4%. After adjusting for inflation, average hourly earnings fell 0.3% over the year.
That gap helps explain why headline economic statistics can look respectable while household sentiment remains weak. Consumers experience the economy through grocery bills, gasoline, insurance, rent, mortgages and monthly payments. When those expenses rise faster than purchasing power, a strong stock market or solid employment backdrop may provide little comfort.
It also explains why targeting one expensive product at a time has limited power. Reducing beef prices does little for someone struggling with a mortgage. Cheaper diesel can eventually help transportation costs, but it cannot repair housing affordability. Cash payments might temporarily improve household finances, while also adding fresh demand for goods and services.
The affordability problem is interconnected.
The Bond Market May Be the Bigger Warning
Investors should pay particular attention to Treasury yields because borrowing costs can overwhelm smaller improvements elsewhere in the economy.
The Treasury Department announced in August that it would at least double the maximum size of certain buybacks of longer-dated Treasury securities, from $2 billion to at least $4 billion per operation beginning September 9. Treasury describes the program as an effort to support liquidity in longer-dated securities rather than a direct attempt to force long-term rates lower.
That distinction matters. Washington can influence market structure, but investors ultimately determine the yield they demand to hold government debt. Inflation expectations, federal borrowing, economic growth, Federal Reserve policy and competing demands for capital all feed into that decision.
Consumers are already feeling the consequences. Freddie Mac’s weekly survey put the average 30-year fixed mortgage at 7.03% on September 24, up from 6.95% the previous week and 6.30% a year earlier.
At 7%, principal and interest on a $300,000 mortgage are roughly $1,996 per month. At 6.5%, the payment is about $1,896. That difference of roughly $100 per month comes from only half a percentage point.
Higher Treasury yields can therefore undermine affordability even if Washington manages to shave a few dollars from grocery or fuel bills.
Where Investors Should Look
Bonds
Persistently high long-term yields remain a headwind for rate-sensitive assets. Housing, commercial real estate, utilities and heavily leveraged companies become more vulnerable as refinancing costs rise.
The key question is whether inflation and fiscal concerns remain strong enough to keep investors demanding elevated yields. If they do, affordability pressure could remain stubborn even if energy or food prices improve.
Consumer Stocks
Household pressure can push consumers toward discount retailers, private-label goods and lower-cost alternatives. Businesses that depend on discretionary spending may face more resistance as consumers devote more of their budgets to housing, food, insurance and fuel.
That creates a growing divide between companies selling necessities or value and those relying on optional purchases.
Energy
Diesel deserves particular attention because it sits deep inside the economy. It powers trucking, agriculture, construction and industrial activity, which means higher diesel costs can work their way into the prices of many other goods.
Any policy that changes refinery incentives or export economics could therefore have second-order effects well beyond the pump.
Inflation-Sensitive Assets
If investors conclude that fiscal policy will remain expansionary while inflation stays above target, demand for inflation-sensitive assets could remain elevated.
That environment can influence Treasury yields, precious metals and other real assets, especially if markets begin to question how quickly inflation can return to the Fed’s 2% goal.
The Affordability Triangle
A simple way to evaluate whether conditions are truly improving is to watch three forces: prices, income and financing.
First, are prices actually cooling across food, energy, shelter and services? Second, are wages rising faster than those prices? Third, are Treasury yields, mortgage rates and other consumer borrowing costs moving lower?
A genuine improvement in household affordability probably requires progress in more than one corner of that triangle. Lower gasoline prices help, and so do cheaper groceries, but if mortgage rates remain around 7% and real hourly earnings are falling, many households will still feel squeezed.
That makes the bond market almost as important to the affordability story as the Consumer Price Index.
The $5,000 Checks Show the Policy Dilemma
The proposed $5,000 payment illustrates the challenge especially well.
Sending households cash would immediately increase disposable income. For families dealing with elevated expenses, that would provide real short-term financial capacity. The broader economic impact, however, would depend heavily on how the program was designed, financed and spent.
If a large portion of the money quickly entered the economy through consumer spending, demand could increase sharply. If the supply of goods and services failed to rise alongside it, some of that extra demand could show up as higher prices.
Bond investors could also respond to a large new federal spending commitment by demanding higher yields if they believed it would increase deficits or inflation pressure. That would raise borrowing costs across mortgages and other consumer loans.
The result could create an uncomfortable chain reaction:
Government relief → stronger demand → inflation concerns → higher bond yields → higher borrowing costs
That outcome is far from guaranteed, especially because no detailed legislation for the proposed dividend has been enacted. Still, investors should pay as much attention to how any payment would be financed as to the size of the check itself.
The Signals That Matter Now
Several developments will show whether affordability pressure is genuinely beginning to ease.
First, watch monthly inflation data, especially gasoline, food and shelter. August’s 3.4% headline inflation rate remains above the Federal Reserve’s 2% target, and renewed energy pressure could make further progress harder.
Second, watch real wages. If nominal pay begins consistently outpacing inflation again, household purchasing power can recover without requiring one-off government interventions.
Third, watch the 10-year Treasury and mortgage rates. Falling borrowing costs would potentially provide broader relief than changes in any single grocery item.
Fourth, watch Congress for details on the proposed $5,000 dividend. Until lawmakers establish eligibility, funding and authorization, investors have little basis for modeling its actual fiscal impact.
Finally, watch energy policy. Diesel has an unusually broad economic footprint, so policies affecting refinery output or exports can spread quickly through transportation and production costs.
About Author