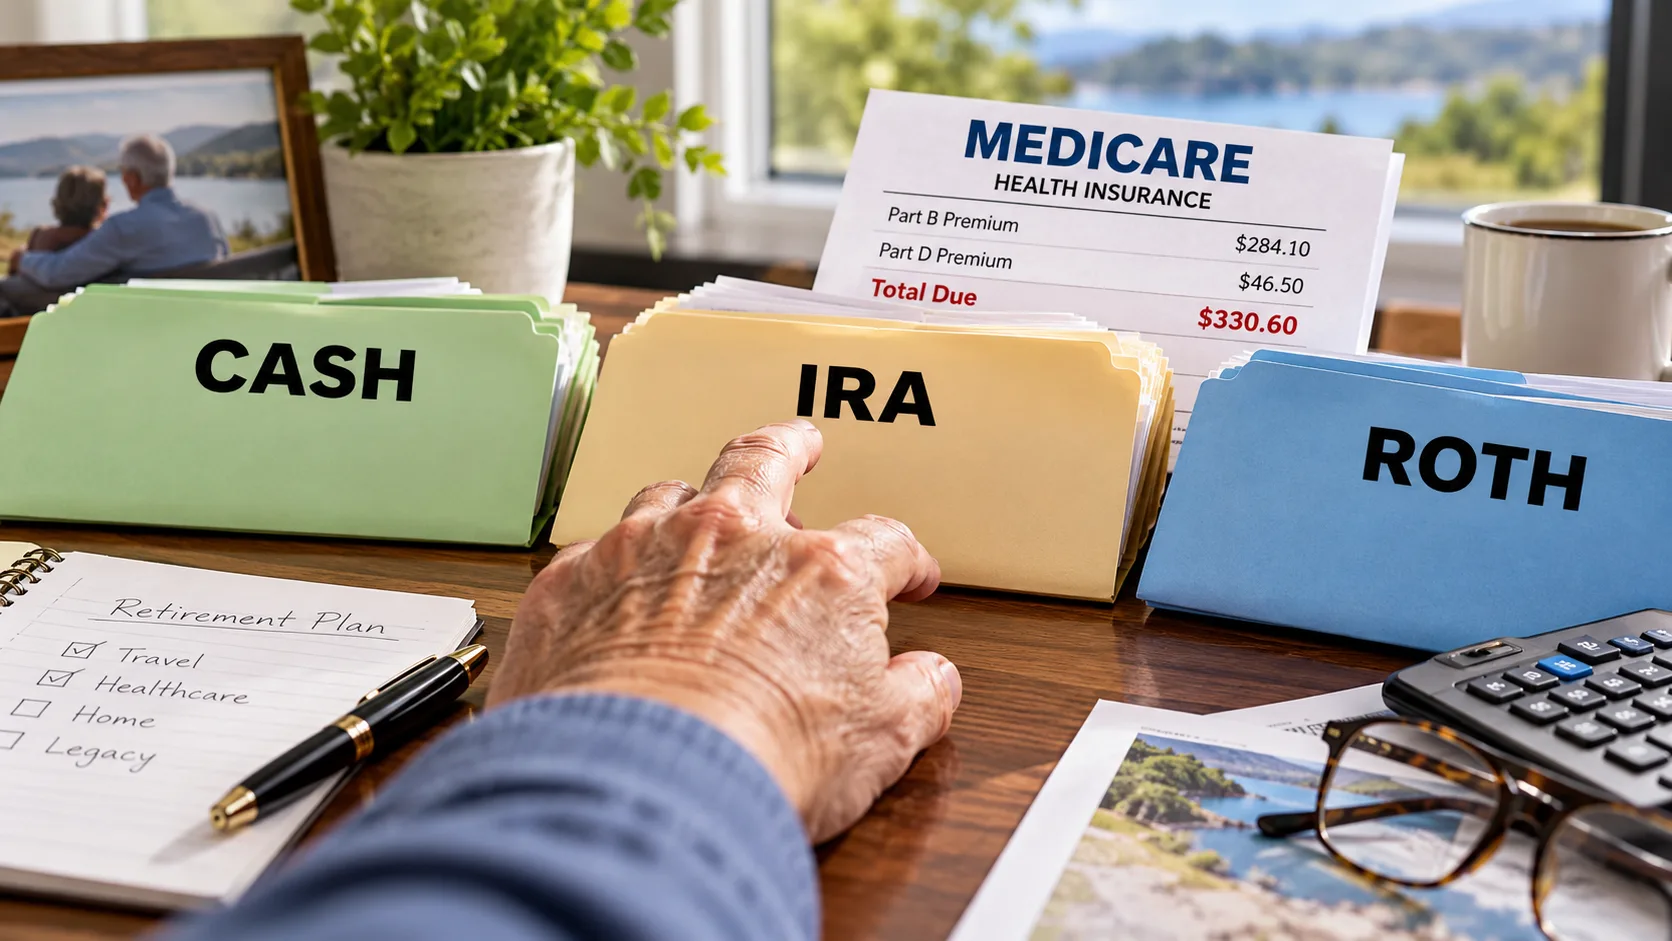
Millions of retirees follow a simple strategy: collect Social Security, use their cash savings to cover expenses, and leave their retirement accounts untouched for as long as possible. But that approach could create a costly tax problem later in life, including higher Medicare premiums.
The order in which retirees withdraw their money can have a significant impact on how much they ultimately keep. Spending cash first while allowing traditional IRAs to grow may seem sensible, especially for retirees who want to preserve their investments. However, required minimum distributions (RMDs) can eventually force retirees to withdraw more taxable income than they need.
For Americans approaching their 70s, understanding how to balance cash withdrawals, IRA distributions, and Roth conversions could make a meaningful difference in their retirement finances.
Why Spending Cash First Can Backfire
Consider a hypothetical retired couple, both age 72, who have built a substantial financial cushion.
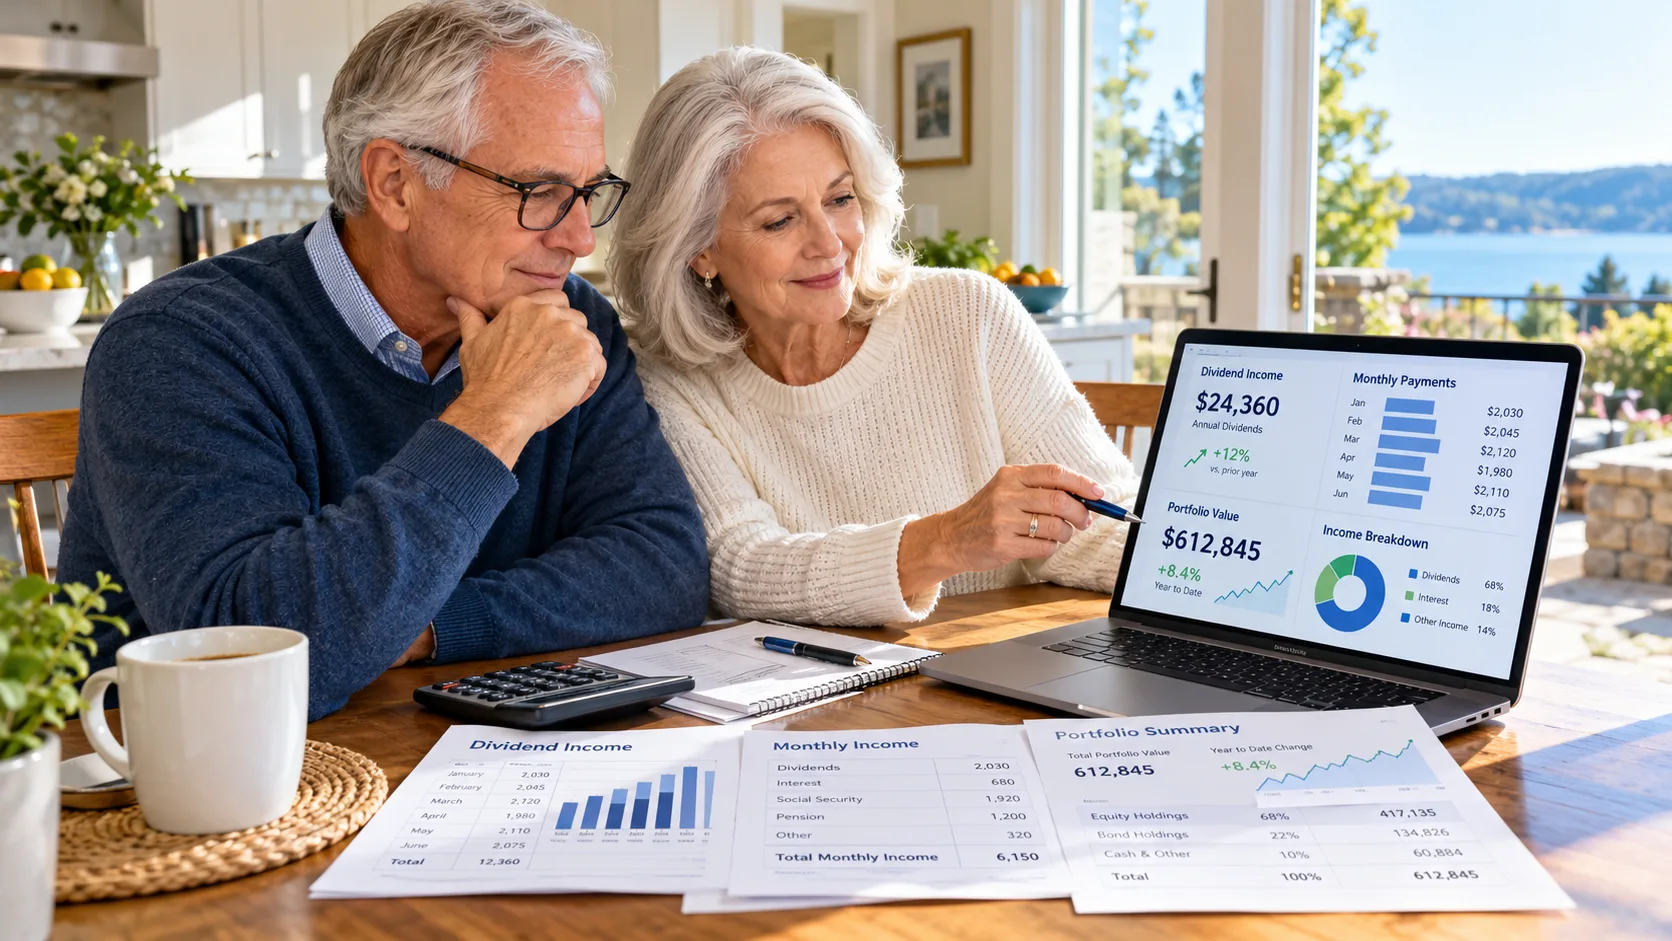
They receive approximately $90,000 annually from Social Security and another $22,000 from fixed annuities, providing $112,000 in annual income before tapping their savings.
Their assets include:
- $500,000 in cash savings
- $900,000 in a traditional rollover IRA
- $180,000 in a Roth IRA
- $800,000 in home equity
- $750,000 in life insurance cash surrender value
With no mortgage or other debt, the couple appears financially secure. Their Social Security and annuity income alone provides approximately $9,333 per month before taxes.
Their retirement strategy is straightforward: use their guaranteed income and cash savings first, begin withdrawing from the traditional IRA when required, preserve the Roth IRA for later years, and maintain their life insurance as a potential source of long-term-care funding.
The problem is that leaving the traditional IRA untouched could eventually increase their tax burden.
While the couple spends down their cash, their $900,000 IRA may continue growing. Once mandatory distributions begin, the government requires them to withdraw a percentage of that account each year, regardless of whether they need the income.
That additional taxable income could push them into higher tax brackets and trigger Medicare surcharges.
Required Minimum Distributions Could Create a Growing Tax Problem
Under current IRS rules, most traditional IRA owners must begin taking required minimum distributions at age 73. The annual withdrawal is calculated using the account balance at the end of the previous year and an IRS life-expectancy factor.
For someone turning 73 with a traditional IRA worth $900,000, the first RMD would be approximately $33,962.
That money generally counts as ordinary taxable income.
If the account continues growing, future withdrawals could become substantially larger. Even after taking the required distributions, the IRA balance might continue increasing if investment returns exceed the amount withdrawn.
Consider how withdrawal requirements change with age.
| Age | Required withdrawal percentage |
|---|---|
| 73 | 3.77% |
| 75 | 4.07% |
| 80 | 4.95% |
| 85 | 6.25% |
| 90 | 8.20% |
Percentages are based on the IRS Uniform Lifetime Table and assume the standard distribution factors apply. Actual withdrawals depend on the prior year-end account balance.
At age 80, a retiree with a $1 million traditional IRA would generally be required to withdraw approximately $49,500. At age 90, the required withdrawal on that same balance would rise to approximately $82,000.
For retirees already receiving substantial Social Security benefits, pensions, or annuity payments, those distributions can create significant additional taxable income.
The result is a financial situation that some retirees overlook: they may have more taxable income in their 80s than they anticipated when they first retired.
The Medicare Penalty Many Retirees Overlook
One of the biggest potential consequences of larger IRA withdrawals involves Medicare’s Income-Related Monthly Adjustment Amount, commonly called IRMAA.
IRMAA adds surcharges to Medicare Part B and Part D premiums when a retiree’s modified adjusted gross income exceeds certain thresholds.
For 2026, the first IRMAA threshold is $218,000 for married couples filing jointly and $109,000 for individual taxpayers.
Here is how Medicare Part B premiums change as income increases.
| 2026 income, married filing jointly | Monthly Part B premium per person |
|---|---|
| $218,000 or less | $202.90 |
| Above $218,000 to $274,000 | $284.10 |
| Above $274,000 to $342,000 | $405.80 |
| Above $342,000 to $410,000 | $527.50 |
| Above $410,000 to below $750,000 | $649.20 |
| $750,000 or more | $689.90 |
Source: Centers for Medicare & Medicaid Services. Additional Part D surcharges apply at these income levels. The 2026 thresholds are based generally on 2024 income and will change in future years.
A married couple whose income moves just above the first threshold would pay an additional $1,948.80 annually in combined Part B premiums, plus applicable Part D surcharges.
These costs can grow considerably at higher income levels. Medicare also generally calculates IRMAA using tax information from two years earlier, meaning a large retirement-account withdrawal today could affect premiums two years from now.
There is another complication for married retirees.
If one spouse dies, the survivor generally faces the lower individual IRMAA thresholds. Although household income may decline, the surviving spouse could still receive sizable IRA distributions and may move into higher tax brackets as a single filer.
That creates an additional reason to consider tax planning before retirement accounts become too large.
Roth Conversions Could Help Reduce Future Taxes
One strategy for addressing this problem is to gradually convert money from a traditional IRA into a Roth IRA.
With a Roth conversion, retirees move money from their pretax retirement account into a Roth account and generally pay ordinary income tax on the amount converted.
The potential advantage comes later.
Qualified Roth IRA withdrawals are tax-free, and Roth IRAs owned by the original account holder are generally exempt from lifetime required minimum distributions.
That gives retirees more control over their future taxable income.
For example, someone with a $900,000 traditional IRA might consider converting $40,000 annually for four years, moving $160,000 into a Roth account before accounting for investment performance and taxes.
That would reduce the amount remaining in the traditional IRA and potentially lower future mandatory withdrawals.
However, conversions require careful planning.
Adding $40,000 to taxable income in a single year could push a retiree into a higher marginal tax bracket or above an IRMAA threshold. The additional Medicare charges could erase some of the anticipated tax savings.
For retirees already subject to RMDs, the required distribution must be satisfied first. The RMD itself cannot be converted into a Roth IRA.
The objective is to convert money during years when the current tax cost is expected to be lower than the future tax cost.
For retirees with substantial cash reserves, paying conversion taxes from outside the IRA may help preserve more money inside the Roth account for potential tax-free growth.
Still, converting too much can also be expensive. The most effective approach depends on current tax brackets, anticipated future income, investment returns, and expected retirement expenses.
Why Using Several Retirement Accounts May Work Better
Rather than completely exhausting one account before moving to the next, some retirees may benefit from withdrawing money from multiple sources each year.
A coordinated approach might combine traditional IRA withdrawals, cash savings, and occasional Roth distributions.
Each source has different tax consequences.
Cash savings: Spending existing after-tax cash generally does not create additional taxable income, although interest earned on the savings is typically taxable.
Traditional IRAs: Withdrawals generally count as ordinary income and may affect both federal taxes and Medicare premiums.
Roth IRAs: Qualified withdrawals are generally tax-free and provide flexibility during years when taking additional taxable income would be expensive.
By combining these sources, retirees may have greater control over their annual tax bills.
For instance, a couple needing an additional $60,000 beyond Social Security and annuity income could consider taking $20,000 from their traditional IRA, $20,000 from cash savings, and $20,000 from their Roth IRA.
That is simply an illustration. An equal three-way split will rarely be the ideal strategy for every household.
Some years, taking more from a traditional IRA could make sense, especially when taxable income is relatively low. In other years, relying more heavily on cash or qualified Roth withdrawals could help avoid moving into a higher tax bracket or triggering Medicare surcharges.
The key is evaluating the tax consequences of withdrawals across several years rather than treating each retirement account separately.
Spending More in Retirement May Also Be Reasonable
Taxes are only one part of retirement planning. Retirees also need to determine how much they can comfortably spend while preserving sufficient assets for future expenses.
For the hypothetical couple described earlier, a retirement-planning illustration using Boldin software estimated a 99% probability of financial success with ordinary spending of $10,000 per month, plus $10,000 annually for additional expenses such as travel over 10 years.
Increasing ordinary spending to $12,000 per month lowered the estimated success rate to 77%. At $15,000 per month, the estimated probability dropped below 50%.
These figures come from a particular set of modeling assumptions and should not be treated as universal spending guidelines. Investment returns, inflation, longevity, insurance coverage, and healthcare expenses can materially change the results.
Nevertheless, the example highlights an important issue.
Some retirees may be so focused on preserving their savings that they unnecessarily restrict their spending during the years when they are healthiest and most able to travel or enjoy retirement.
A carefully constructed withdrawal strategy can help retirees determine how much they can spend today while retaining resources for emergencies and future care.
Long-Term Care Can Change the Tax Equation
Another consideration is how retirees plan to pay for potential long-term-care expenses.
Assisted living, nursing-home care, and in-home assistance can create substantial costs later in retirement. Depending on the circumstances, certain qualifying medical and long-term-care expenses may also generate tax deductions.
That possibility can make traditional IRA withdrawals more attractive during years when large deductible healthcare bills arise.
Consequently, converting every available dollar from a traditional IRA into a Roth may not always produce the best outcome.
Life insurance can also provide another potential funding source. However, retirees planning to use a policy’s cash surrender value should evaluate surrender charges, potential tax consequences, death-benefit reductions, and whether the policy includes any long-term-care benefits.
Cash surrender value alone does not provide the same protection as a dedicated long-term-care insurance policy.
Four Things Retirees Should Review Before Their Next Withdrawal
For Americans approaching their 70s, several planning decisions deserve attention.
1. Estimate future required minimum distributions. Project traditional IRA balances and mandatory withdrawals at ages 73, 80, 85, and 90. Consider how those withdrawals will combine with Social Security, pensions, annuities, and other taxable income.
2. Review Medicare income thresholds. Identify whether planned IRA distributions, investment gains, or Roth conversions could push household income into an IRMAA bracket. Remember that premium increases typically arrive two years after the income is reported.
3. Compare multiyear Roth conversion strategies. Evaluate smaller conversions spread over several years against larger conversions and a strategy involving no conversions. Account for both income taxes and Medicare premiums.
4. Plan for the surviving spouse. Consider how reduced Social Security income, single-filer tax brackets, and lower Medicare surcharge thresholds could affect household finances after one spouse dies.
Retirees should revisit these calculations periodically as account balances, spending needs, tax laws, and Medicare thresholds change.
The Takeaway for Retirees
The traditional retirement strategy of spending cash first and preserving IRA savings can provide flexibility in the early years of retirement. However, leaving large pretax retirement accounts untouched for too long can create unnecessary tax complications later.
Required minimum distributions, higher Medicare premiums, and changing tax brackets can all reduce the amount retirees ultimately keep.
For many households, the better approach may be to coordinate withdrawals across cash savings, traditional IRAs, and Roth accounts while considering selective Roth conversions.
The goal is to maintain enough flexibility to manage taxes throughout retirement, protect against unexpected expenses, and enjoy the savings accumulated over decades of work.
Retirees who plan when to withdraw their money may be able to keep more of it, without sacrificing the lifestyle they worked to achieve.
About Author