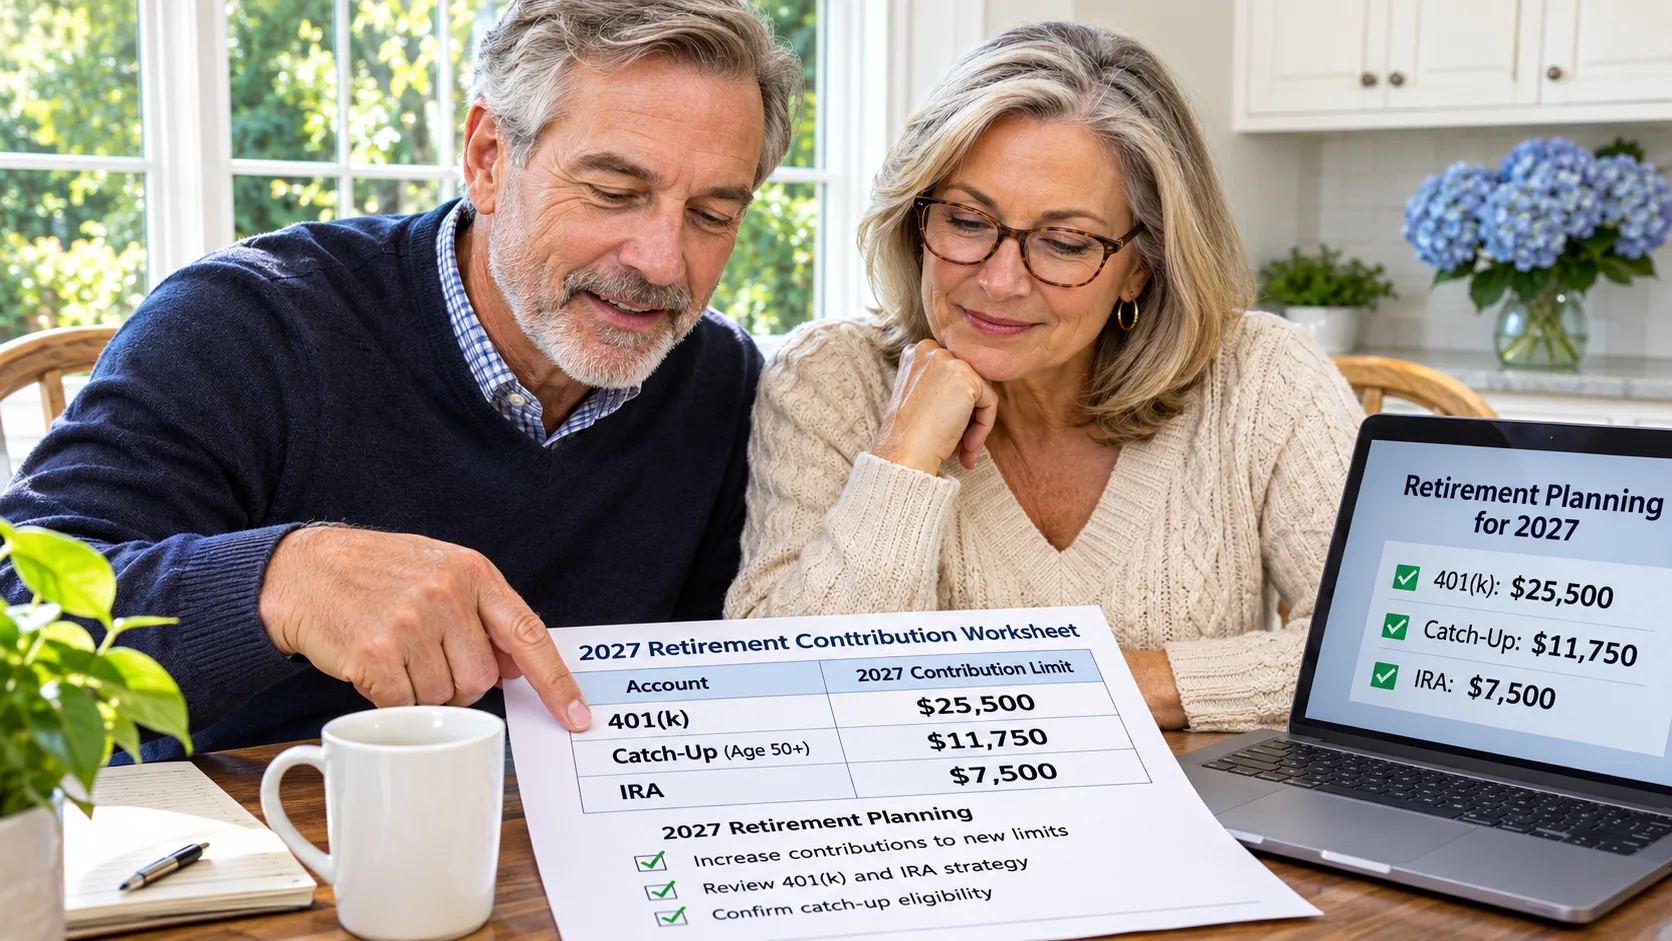
From Social Security decisions to overlooked IRS rules, these 11 retirement milestones could make a significant difference in how much money Americans keep during retirement.
For Americans over 50, some of the biggest retirement mistakes have nothing to do with the stock market. Missing an important deadline, claiming benefits too early, or overlooking a tax-saving opportunity could quietly affect your finances for decades.
And with several retirement rules changing in 2027, knowing when to act is becoming increasingly important.
The IRS has announced higher retirement contribution limits for next year, while rules governing Social Security, Medicare premiums, and retirement withdrawals create additional opportunities for people who plan ahead.
The challenge is that many of these benefits become available at specific ages, and some opportunities disappear just a few years later. Others involve decisions that are difficult or impossible to reverse.
Here are 11 important retirement milestones every American over 50 should understand.
Why Retirement Planning Changes After Age 50
During their working years, most Americans focus on building their retirement savings. The goal is relatively straightforward: contribute regularly, invest wisely, and allow compound growth to do its work.
After age 50, retirement planning becomes more complicated. Decisions about when to withdraw money, which accounts to use, and when to begin collecting Social Security can have financial consequences that last for decades.
There is also an increasingly important relationship between retirement income and taxes. Withdrawing money from a traditional IRA, converting savings to a Roth account, or claiming Social Security at the wrong time could create unexpected tax consequences.
Medicare adds another layer of complexity. Certain financial decisions made at age 63, for example, can directly affect what someone pays for Medicare at age 65.
Understanding how these rules fit together is essential to protecting the retirement savings Americans have spent decades building.
The 11 Retirement Milestones You Need to Know
11 Important Retirement Milestones
A quick reference guide for Americans over 50.
| Age | Milestone |
|---|---|
| 50 | Retirement catch-up contributions |
| 55 | Rule of 55 and larger HSA contributions |
| 59½ | Penalty-free retirement withdrawals |
| 60–63 | Enhanced 401(k) catch-up contributions |
| 62 | Earliest Social Security retirement benefits |
| 63 | Medicare’s two-year income lookback |
| 65 | Medicare enrollment and senior tax deduction |
| 67 | Full Social Security age for those born 1960+ |
| 70 | Maximum Social Security delayed credits |
| 70½ | Qualified charitable distributions |
| 73 or 75 | Required minimum distributions begin |
Source: IRS, Social Security Administration and Medicare. Individual eligibility and deadlines may vary.
1. Age 50: Start Making Larger Retirement Contributions
Turning 50 unlocks one of the simplest opportunities to strengthen retirement savings: catch-up contributions.
These provisions allow older workers to contribute more money to tax-advantaged retirement accounts beyond the standard annual limits. They are particularly valuable for Americans who started saving later in life or want to maximize contributions during their highest-earning years.
For 2027, employees can contribute up to $25,500 to most 401(k) plans. Workers age 50 and older can contribute an additional $8,500, bringing their annual contribution limit to $34,000.
Individual retirement accounts also provide additional savings opportunities. In 2027, eligible savers age 50 and older can contribute up to $8,600 to traditional and Roth IRAs combined, including a $1,100 catch-up allowance. Income restrictions and other eligibility requirements may apply. Internal Revenue Service+1
There is also an important change for higher-income workers. Beginning in 2027, employees who earned more than $155,000 in Social Security-taxable wages from their employer in 2026 generally must direct their workplace catch-up contributions into Roth accounts.
That means paying income taxes on those contributions now in exchange for the potential benefit of tax-free qualified withdrawals in retirement.
Why it matters: The years after 50 can be some of the most important for retirement savings. Maximizing catch-up contributions may help close savings gaps while there is still time for those investments to grow.
2. Age 55: A Little-Known Rule Could Unlock Your 401(k) Early
Most Americans know that withdrawing money from a 401(k) before age 59½ can trigger a 10% early-withdrawal penalty. However, an exception known as the Rule of 55 may allow certain workers to access their retirement savings earlier.
Under this provision, individuals who leave their jobs during or after the calendar year they turn 55 may qualify for penalty-free withdrawals from that employer’s retirement plan.
The rule can apply whether someone retires voluntarily, is laid off, or otherwise separates from employment. Ordinary income taxes generally still apply to withdrawals from traditional pretax accounts.
There is an important limitation. The Rule of 55 generally applies only to the qualifying workplace retirement plan associated with the employer the person leaves. It does not automatically apply to IRAs or retirement plans maintained with previous employers.
People considering early retirement should also confirm that their employer’s plan permits the distributions they intend to take.
Turning 55 provides another opportunity through health savings accounts. For 2027, eligible individuals age 55 and older can contribute an additional $1,000 annually to an HSA, bringing potential contribution limits to $5,500 for individual coverage and $10,000 for family coverage. IRS+1
Why it matters: For someone planning to retire before 60, understanding the Rule of 55 could provide greater financial flexibility and help avoid unnecessary early-withdrawal penalties.
3. Age 59½: Retirement Savings Become Easier to Access
Reaching age 59½ marks another important turning point. At this age, withdrawals from traditional IRAs and most qualified workplace retirement accounts generally become exempt from the usual 10% federal early-withdrawal penalty.
However, avoiding the penalty does not necessarily mean avoiding taxes. Withdrawals from traditional pretax accounts generally remain subject to ordinary income tax.
Roth retirement accounts operate differently. Qualified withdrawals from Roth IRAs can be entirely tax-free, but withdrawing earnings generally requires meeting both the age 59½ requirement and a five-tax-year holding period.
For retirees with substantial savings in traditional accounts, this milestone also presents an opportunity to evaluate Roth conversions.
Converting money from a traditional IRA into a Roth IRA generally creates taxable income in the year of conversion. However, strategically spreading conversions over several years may reduce future required minimum distributions and create greater flexibility when managing retirement income.
Why it matters: The years between leaving the workforce and beginning Social Security or mandatory withdrawals can create valuable tax-planning opportunities, particularly for retirees whose taxable income temporarily declines.
4. Ages 60–63: A Four-Year Opportunity to Save Even More
One of the most significant retirement savings changes introduced under SECURE 2.0 is an enhanced catch-up contribution for workers ages 60 through 63.
Beginning in 2027, eligible employees in this age group can contribute an additional $11,750 to most 401(k) plans beyond the standard annual employee contribution limit.
That brings the potential annual contribution to $37,250, compared with $34,000 for most other workers age 50 and older.
2027 401(k) Contribution Limits
How much employees can potentially contribute based on age.
Source: IRS, 2027 retirement plan limits. Assumes an eligible workplace plan. Employer contributions and certain plan-specific limits are separate.
For workers who can afford to maximize their savings, this temporary window offers an opportunity to contribute substantially more during the final years before retirement.
The enhanced allowance disappears after age 63, making it important to understand the timing. Higher-income workers subject to the Roth catch-up requirement must also consider the immediate tax implications of these additional contributions. Internal Revenue Service+1
Why it matters: Workers who overlook this four-year window could miss thousands of dollars in additional tax-advantaged contribution capacity during a critical period before retirement.
5. Age 62: Social Security Becomes Available, but There Is a Catch
Age 62 is the earliest most Americans can begin collecting Social Security retirement benefits.
For someone eager to retire, receiving a monthly government payment five years before full retirement age can be appealing. However, claiming early permanently reduces the monthly benefit compared with waiting until full retirement age.
For Americans born in 1960 or later, full retirement age is 67. Claiming at 62 generally reduces the retirement benefit by 30%.
Consider someone entitled to receive $2,500 per month at full retirement age. Claiming at 62 would reduce that amount to approximately $1,750, while waiting until 70 would increase it to roughly $3,100, before future cost-of-living adjustments.
How Claiming Age Affects Social Security
Illustrative monthly benefits based on $2,500 at full retirement age.
Illustrative example for someone with a full retirement age of 67. Actual benefits vary. Amounts exclude future COLAs, taxes and Medicare deductions.
There is another complication for Americans who continue working while receiving Social Security before full retirement age.
In 2027, individuals who remain below full retirement age for the entire year can earn up to $25,560 before Social Security begins withholding $1 in benefits for every $2 earned above that limit.
Benefits withheld because of the earnings test are accounted for through a later recalculation, meaning they are not necessarily permanently lost. SSA+1
Claiming early can still make sense for individuals facing health problems, financial pressures, or shorter life expectancies. For those expecting a long retirement, however, the reduction in monthly income deserves careful consideration.
Why it matters: Choosing when to claim Social Security can affect retirement income for decades, making it one of the most consequential financial decisions many Americans will face.
6. Age 63: A Tax Decision Today Could Raise Medicare Premiums Later
This is one of the most overlooked retirement planning milestones.
Medicare generally calculates certain premium surcharges using income reported on federal tax returns from two years earlier. That means financial decisions made at age 63 can directly affect Medicare premiums at age 65.
The additional charge is known as an income-related monthly adjustment amount, or IRMAA. It applies to higher-income beneficiaries and can increase the cost of Medicare Parts B and D.
For 2027, individuals with modified adjusted gross income above $112,000 and married couples filing jointly with income above $224,000 generally enter the first Medicare surcharge bracket, based on their 2025 income.
The standard Medicare Part B premium for 2027 is $209.40 per month. Crossing the first IRMAA threshold increases that premium to $293.10, with larger increases applying at higher income levels. CMS+1
Consider someone who makes a large Roth IRA conversion at age 63. The conversion could generate enough taxable income to move that person into a higher Medicare premium bracket two years later, even if their normal retirement income remains unchanged.
The same issue can arise from significant capital gains, large traditional IRA withdrawals, or other taxable events.
Certain life-changing circumstances, including retirement or reduced employment, may qualify beneficiaries to request a reconsideration of their Medicare surcharge. However, that possibility should not replace careful advance planning.
Why it matters: A tax strategy that appears attractive today could create higher healthcare costs later. Coordinating Roth conversions, investment sales, and retirement withdrawals with Medicare income thresholds can help avoid surprises.
7. Age 65: Medicare Enrollment and an Additional Tax Deduction
Turning 65 introduces two major financial considerations: Medicare enrollment and a potentially valuable federal income-tax deduction.
Most Americans become eligible for Medicare at age 65, with an initial enrollment period lasting seven months. That includes the three months before the birthday month, the birthday month itself, and the following three months.
Missing the enrollment window can create coverage gaps and permanent premium penalties for individuals who do not qualify for an exception.
For Medicare Part B, the standard late-enrollment penalty is generally 10% for each full 12-month period someone could have enrolled but failed to do so. Special enrollment rules may apply to people who continue working and maintain qualifying employer coverage.
Medicare enrollment also affects health savings accounts. Once someone enrolls in Medicare, they generally cannot continue making new HSA contributions for covered months, although existing HSA funds can still be used for eligible medical expenses and certain Medicare premiums.
The second opportunity comes from a federal income-tax deduction established in 2025.
Eligible taxpayers age 65 and older may claim an additional deduction of up to $6,000 per person through tax year 2028. Married couples filing jointly can qualify for up to $12,000 if both spouses are eligible.
The deduction begins phasing out when modified adjusted gross income exceeds $75,000 for individual filers or $150,000 for married couples filing jointly. It is available to qualifying taxpayers whether they itemize or take the standard deduction. Internal Revenue Service+1
Why it matters: Medicare enrollment mistakes can increase healthcare costs for years, while overlooking available tax deductions could result in paying more federal income tax than necessary.
8. Age 67: Full Social Security Benefits Become Available
For Americans born in 1960 or later, age 67 represents full Social Security retirement age.
At this point, individuals can begin collecting their full calculated retirement benefit without the permanent reduction associated with claiming early. The Social Security earnings test also ends, allowing people who continue working to earn employment income without having retirement benefits withheld under that rule.
However, Social Security benefits may still be subject to federal income taxes depending on the retiree’s total income.
For married couples, the decision can become more complicated. A higher-earning spouse who delays claiming Social Security may increase the survivor benefit available to the other spouse after their death.
This makes coordinating Social Security benefits especially important for couples with substantial differences in lifetime earnings.
Some retirees may benefit from collecting at 67, while others could improve their long-term financial position by delaying until age 70.
Why it matters: Reaching full retirement age is an opportunity to reassess retirement income needs, investment balances, expected longevity, and the financial security of a surviving spouse.
9. Age 70: The Last Opportunity to Increase Social Security by Waiting
For Americans who can afford to delay Social Security, age 70 offers the maximum monthly retirement benefit based on delayed retirement credits.
For someone whose full retirement age is 67, waiting until 70 increases their benefit by 24%. That increase reflects delayed retirement credits of 8% per year over the three years between ages 67 and 70.
A retiree eligible for $2,500 per month at 67 would receive approximately $3,100 per month at 70, excluding future cost-of-living adjustments.
That represents an additional $7,200 annually before adjustments, which can become significant over a retirement lasting 20 years or more.
However, delaying Social Security also means giving up benefits that could have been collected earlier. The decision should account for life expectancy, retirement savings, other sources of income, and the needs of a spouse.
There is no additional increase in delayed retirement credits after age 70.
Why it matters: Anyone who has delayed Social Security until 70 should evaluate beginning benefits, since waiting longer generally provides no additional retirement credit.
10. Age 70½: Charitable Donations Can Provide Tax Advantages
For retirees who regularly donate to charity, reaching age 70½ unlocks a potentially valuable tax strategy.
Qualified charitable distributions, commonly known as QCDs, allow eligible IRA owners to send money directly to qualifying charitable organizations without including the distribution in their taxable income.
For 2027, the annual QCD exclusion limit increases to $114,000 per eligible IRA owner.
A separate provision permits a one-time election for certain qualifying charitable arrangements, such as eligible charitable gift annuities, with a 2027 limit of $57,000. IRS
QCDs can become particularly useful once required minimum distributions begin.
Eligible charitable distributions can count toward satisfying an IRA owner’s RMD while keeping the distributed amount out of taxable income. This can provide advantages compared with taking a regular taxable withdrawal and then donating the money separately.
The rules are specific, including requirements that the distribution generally go directly from the IRA custodian to the qualified charity.
Why it matters: For retirees already planning to support charitable organizations, QCDs may help manage taxable retirement income while allowing them to continue making meaningful contributions.
11. Ages 73 and 75: Mandatory Retirement Withdrawals Begin
The final milestone involves required minimum distributions, commonly called RMDs.
These are mandatory withdrawals from most traditional tax-deferred retirement accounts, including traditional IRAs and many workplace retirement plans.
Under current federal law, the age when RMDs generally begin depends on when someone was born.
- Born from 1951 through 1959: RMDs generally begin at age 73.
- Born in 1960 or later: RMDs generally begin at age 75.
The amount a retiree must withdraw each year is typically calculated using the account balance at the end of the previous year and an IRS life-expectancy factor.
Missing a required withdrawal can trigger a substantial penalty. The IRS generally imposes a 25% excise tax on the amount that should have been withdrawn, although the penalty can fall to 10% when the mistake is corrected within the permitted correction period.
There are also important exceptions. Eligible workers who remain employed may be allowed to delay RMDs from certain employer-sponsored retirement plans. Roth IRAs and designated Roth accounts in workplace retirement plans are no longer subject to lifetime RMDs for their original owners.
For Americans who have accumulated significant balances in traditional retirement accounts, RMDs can create an unexpected tax problem.
A retiree with a large IRA may be required to withdraw more money annually than needed for living expenses. Those distributions can increase taxable income, potentially pushing the retiree into a higher tax bracket or triggering additional Medicare costs.
Why it matters: Planning for mandatory withdrawals years before they begin can provide more flexibility to manage taxes and retirement income.
The Retirement Tax Trap Many Americans Overlook
One of the biggest retirement planning mistakes is treating Social Security, Medicare, retirement withdrawals, and taxes as separate financial decisions.
In reality, they are closely connected.
Consider a hypothetical 65-year-old retiree with $1 million in traditional retirement accounts. The person plans to delay Social Security until age 70 while using savings to cover living expenses.
During those years, the retiree may have an opportunity to convert portions of traditional retirement savings into a Roth IRA, potentially reducing future required minimum distributions.
However, converting too much money in a single year could generate additional taxable income, push the retiree into a higher tax bracket, and increase Medicare premiums two years later.
Claiming Social Security during those same years would change the calculation again.
The challenge is determining how much income to recognize, which accounts to withdraw from, and when to begin collecting government benefits.
A well-coordinated strategy can potentially reduce total lifetime taxes while preserving financial flexibility.
Why Retirement Tax Planning Can Be as Important as Investment Returns
Consider two hypothetical retirees who each have $1 million invested in traditional retirement accounts.
Both earn identical investment returns and retire at the same age. However, they take different approaches to managing their retirement income.
The first waits until required minimum distributions begin before developing a withdrawal strategy. At that point, mandatory distributions could push a significant amount of money into taxable income each year.
The second begins evaluating withdrawal strategies earlier, taking advantage of lower-income years to consider Roth conversions and other tax-management opportunities.
By the time mandatory withdrawals begin, the second retiree may have reduced the balance subject to RMDs while increasing the amount held in accounts eligible for tax-free withdrawals.
The actual financial benefit will depend on tax rates, conversion costs, investment performance, and individual circumstances. Still, the example illustrates why two people with identical retirement savings can experience very different after-tax outcomes.
What matters most in retirement is how much of your money remains available to spend after taxes and other expenses.
Four Retirement Planning Mistakes Worth Avoiding
As Americans approach retirement, several decisions deserve particular attention.
Claiming Social Security without comparing different ages. Beginning benefits at 62 can make sense for some retirees, but the permanent monthly reduction should be weighed against the advantages of waiting until full retirement age or 70.
Overlooking enhanced retirement contribution opportunities. The additional savings allowances beginning at age 50 and the temporary enhanced catch-up period from ages 60 through 63 can provide meaningful benefits for workers who can afford to contribute more.
Making large taxable withdrawals without considering Medicare. Roth conversions, investment sales, and traditional retirement account withdrawals can trigger Medicare surcharges when they push income above certain thresholds.
Waiting until RMDs begin to plan for retirement taxes. By the time mandatory distributions start, retirees may have missed valuable opportunities to manage the amount of money held in tax-deferred accounts.
What Americans Over 50 Should Review Before 2027
With 2027 approaching, now is a useful time for retirement savers to revisit their financial plans.
The IRS has confirmed higher retirement contribution limits for next year, giving eligible workers additional room to save. Those approaching ages 60 through 63 should pay particular attention to the enhanced catch-up contribution rules, while higher-income employees need to understand the new Roth requirements.
Americans approaching Medicare eligibility should evaluate how their recent and expected taxable income could affect future premiums. Anyone considering substantial Roth conversions, particularly in their early 60s, should understand the two-year income lookback used by Medicare.
Those nearing Social Security eligibility should also compare the benefits of claiming at 62, full retirement age, and 70. That decision may affect household income for decades, particularly for married couples.
These decisions are often best evaluated together, ideally with a qualified financial or tax professional who understands the household’s complete retirement picture.
The Bottom Line
Retirement planning involves much more than building a large investment portfolio. After age 50, a series of important financial milestones creates opportunities to save more, access retirement funds, reduce taxes, and maximize Social Security benefits.
Some decisions can be adjusted later, while others involve permanent financial consequences. Knowing which rules apply and when to act can make a meaningful difference in long-term retirement security.
For Americans approaching retirement, understanding these 11 milestones may be one of the most valuable financial steps they take before 2027.
About Author