Democrats have won control of both chambers of Congress, putting Social Security’s financial future back in the political spotlight. With retirement benefits facing a potential 22% funding shortfall in just six years, millions of Americans have a significant financial stake in what lawmakers do next.
The November 3 midterm elections dramatically changed the balance of power in Washington. Democrats will take control of the House and Senate when the new Congress convenes in January 2027, creating a divided government with President Donald Trump remaining in the White House.
One of the most consequential issues awaiting lawmakers is Social Security’s approaching financial crisis.
The program’s retirement trust fund is projected to exhaust its reserves in 2032. Without changes to the law, incoming revenues would cover just 78% of scheduled retirement and survivor benefits.
That leaves Congress with a difficult choice: raise additional revenue, change benefits, or develop a combination of reforms before the funding gap reaches retirees’ monthly checks.
A New Congress Inherits a $3.8 Trillion Problem
The latest Social Security Trustees Report paints a troubling picture of the program’s finances.
According to the 2026 report, the Old-Age and Survivors Insurance Trust Fund will run out of reserves in the fourth quarter of 2032, one quarter earlier than previously projected.
The Committee for a Responsible Federal Budget estimates that Social Security will accumulate approximately $3.8 trillion in cash deficits over the next decade.
The underlying problem is straightforward. As Americans live longer and the number of retirees grows, Social Security is paying out more than it collects in payroll taxes and other noninterest income.
The program has been drawing down accumulated reserves to cover the difference. Those reserves are shrinking, and the annual funding gap is expected to continue.
Importantly, Social Security would continue collecting payroll taxes even after its retirement trust fund reserves are exhausted. Benefits would not disappear entirely.
However, without congressional action, the program would lack sufficient funds to pay all benefits currently promised under federal law.
What a 22% Social Security Reduction Could Mean for Your Retirement
For retirees who depend on Social Security to cover housing, groceries, utilities, healthcare, and other living expenses, a 22% reduction would have serious consequences.
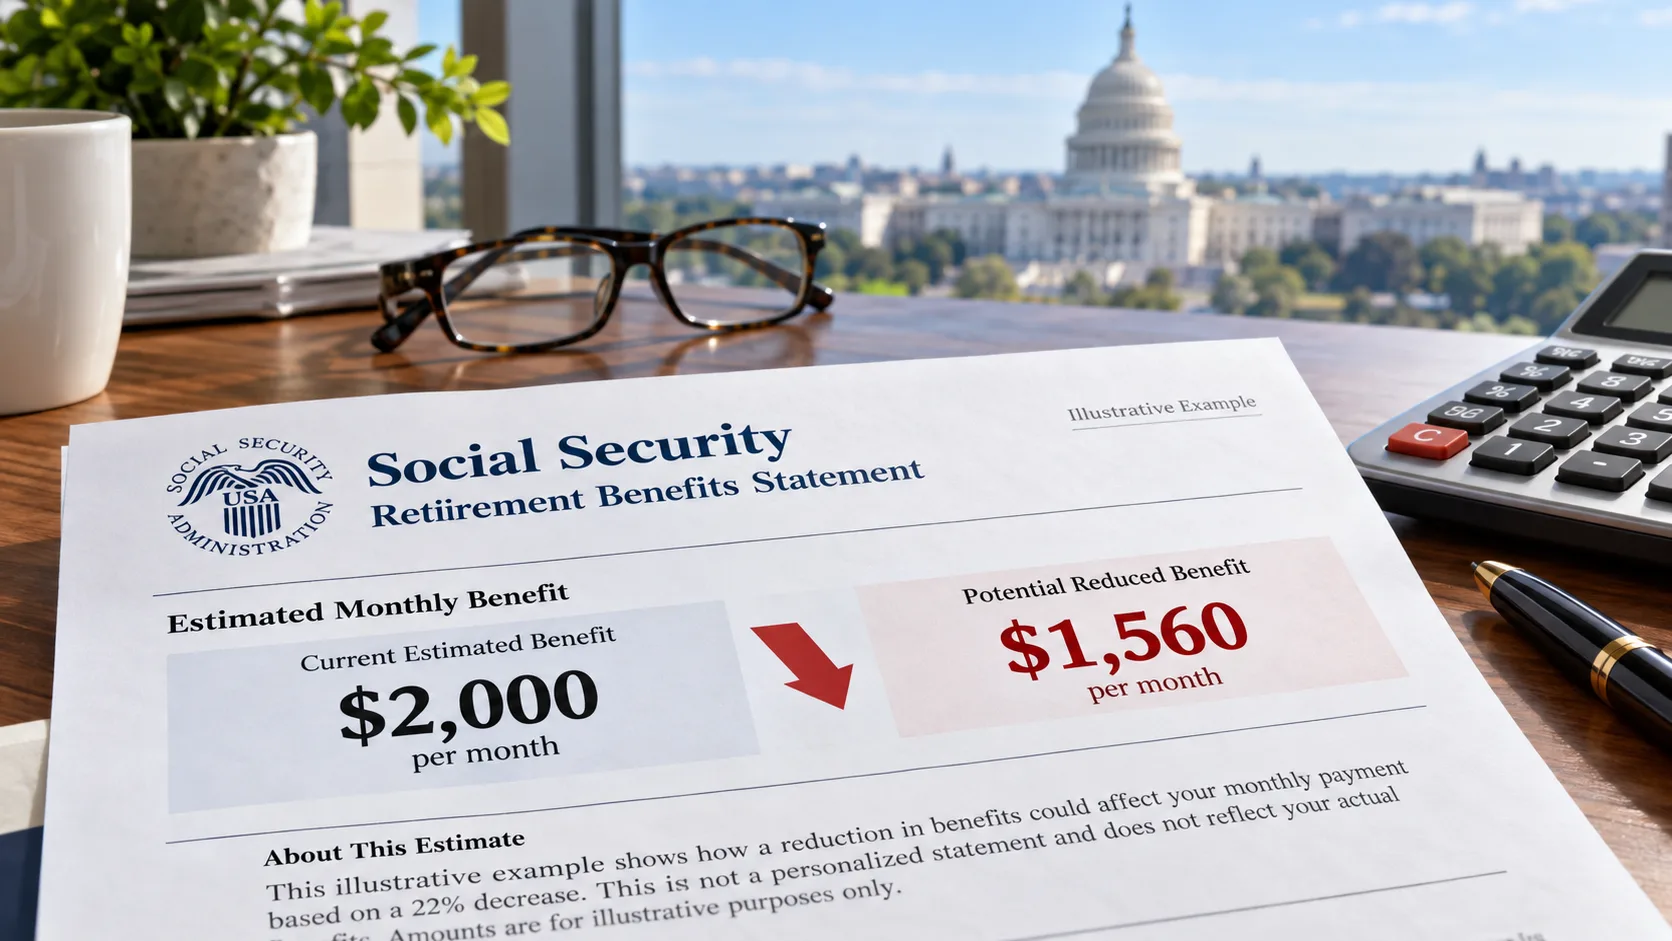
Consider what that would mean for someone receiving $2,000 per month.
Under a hypothetical across-the-board 22% reduction, that monthly payment would fall to $1,560, a loss of $440 every month.
For someone receiving $3,000 monthly, the reduction would amount to $660 per month, or nearly $8,000 annually.
| Current Monthly Benefit | After a 22% Reduction | Annual Income Lost |
|---|---|---|
| $1,500 | $1,170 | $3,960 |
| $2,000 | $1,560 | $5,280 |
| $2,500 | $1,950 | $6,600 |
| $3,000 | $2,340 | $7,920 |
| $4,000 | $3,120 | $10,560 |
These figures are illustrative calculations based on a hypothetical uniform 22% reduction. They are not announced benefit changes or predictions of individual payments.
For households relying on two Social Security checks, the combined financial impact could be substantial.
A reduction of this magnitude could force some retirees to draw more heavily from savings, postpone major purchases, reduce discretionary spending, or reconsider their retirement budgets.
There is another important distinction: the often-cited 22% shortfall applies specifically to the retirement and survivors trust fund in 2032.
If Congress authorized the retirement and disability trust funds to operate on a combined basis, their reserves are projected to last until 2034. At that point, incoming revenues would cover approximately 83% of scheduled benefits, representing a 17% shortfall.
Neither projection means Congress has approved a reduction in benefits. Both illustrate the financial consequences of allowing current funding problems to go unresolved.
Democrats Want to Protect Benefits. The Question Is How to Pay for Them.
Democrats’ election victories give the party greater influence over Social Security legislation, congressional committees, and the national debate over retirement security.
Many Democratic lawmakers have supported proposals to strengthen Social Security by increasing payroll taxes on higher-income Americans while preserving or expanding benefits.
Currently, Social Security payroll taxes apply only to wages up to an annual earnings limit. Income above that threshold is generally exempt from the Social Security portion of the payroll tax.
One frequently discussed proposal would require higher earners to contribute Social Security taxes on additional income.
Supporters argue that changing the taxable earnings limit could generate significant revenue while protecting retirees from benefit reductions.
Opponents of large payroll-tax increases raise concerns about the effects on workers, employers, business owners, and economic activity. Some also question whether taxing higher earners alone would fully close Social Security’s long-term funding gap.
Republican proposals have varied. Many Republican lawmakers have emphasized protecting benefits for current retirees, improving program efficiency, and reducing improper payments. Other proposals discussed over time have included gradually increasing the retirement age or adjusting future benefit formulas.
Each approach carries financial and political consequences.
Raising revenue could extend the program’s solvency, but would increase taxes for affected workers or employers. Changing benefit formulas or retirement eligibility could reduce projected costs, but might require future retirees to work longer or adjust their financial plans.
The central question facing Washington is how to distribute the cost of keeping Social Security financially sustainable.
President Trump Remains a Major Obstacle to Any Agreement
Although Democrats won control of Congress, they will still need to work within a divided federal government.
President Trump retains the power to veto legislation, and most major bills face procedural hurdles in the Senate.
That means Democrats cannot simply pass a sweeping Social Security overhaul and expect it to become law without substantial cooperation.
A lasting agreement could require negotiations involving Democratic congressional leaders, Senate Republicans, and the White House.
The possibility of bipartisan action is not entirely theoretical.
In July 2026, lawmakers from both parties introduced the PROMISE Act, a proposal intended to initiate congressional action on Social Security’s approaching financial shortfall.
The bipartisan effort demonstrated that members of both parties recognize the urgency of the problem, even as they disagree over potential solutions.
Still, launching negotiations is considerably easier than reaching agreement on how to finance benefits over the coming decades.
The Biggest Risk May Be Congress Waiting Too Long
One of the less-discussed consequences of Social Security’s funding problems is that delaying reform can make the eventual solution more difficult.
When changes are implemented years in advance, lawmakers have more flexibility to phase in tax increases or benefit adjustments gradually.
If Congress waits until trust fund reserves are nearly exhausted, the available choices become more immediate and potentially more disruptive.
A late agreement could require larger revenue increases, more substantial spending changes, or some combination of both.
For people nearing retirement, that uncertainty creates a financial planning problem.
Someone who is 60 today will be approximately 66 when the retirement trust fund is projected to exhaust its reserves in 2032. A person who is 55 will be approaching the traditional retirement years.
These are Americans making decisions right now about when to stop working, how much to withdraw from retirement accounts, and when to begin collecting Social Security.
The longer Washington postpones a funding agreement, the harder it becomes for those households to plan with confidence.
The Stakes Are Too High to Ignore
The 2026 midterm elections have given Democrats control of Congress and opened a new chapter in Washington’s debate over Social Security.
But the program’s financial challenges existed before the election, and they will remain regardless of which party controls Congress.
The retirement trust fund is projected to exhaust its reserves in 2032. Without legislative changes, the resulting funding gap could have significant consequences for millions of retirees.
Congress still has time to act, and a range of potential solutions remains available.
For Americans already retired or approaching retirement, the critical question is whether lawmakers can reach an agreement before the financial pressure becomes unavoidable.
The election has changed who controls Congress. The next challenge is determining who will pay to secure Social Security’s future.
About Author